Our Data Processing Agreement changes on 2 November 2026.
Version 3.0 changes what it says about how our AI service providers handle the data we send them. There is no new sub-processor.
Read what is changing
Our Privacy Policy changes on 9 November 2026.
Version 5.1 updates how we use information about your use of Opagio and our emails, how we handle enquiries, and the service providers that help us.
Read what is changing
By Tony Hillier· 2026-03-16purchase price allocationPPAIFRS 3ASC 805FRS 102intangible asset valuationgoodwillbusiness combinationsacquisition accountingfair value measurement
What Is Purchase Price Allocation?
Purchase price allocation (PPA) is the accounting exercise an acquirer performs after buying a business: it measures the consideration paid, assigns fair values to the identifiable assets acquired and liabilities assumed, including intangible assets the seller never recognised, and records whatever is left over as goodwill. It is required for business combinations under IFRS 3 Business Combinations, under ASC 805 in US GAAP and under Section 19 of FRS 102 in the UK and Ireland.
PPA is not an optional accounting exercise. It is a reporting requirement with material financial consequences: the allocation sets the acquirer's future amortisation expense, its deferred tax, its impairment exposure and how clearly its accounts explain what it bought.
Last reviewed: October 2026. Reflects IFRS 3, ASC 805 and FRS 102 as amended by the FRC's Periodic Review 2024, which applies to accounting periods beginning on or after 1 January 2026.
12 monthsmeasurement period to finalise the PPA (IFRS 3, ASC 805 and FRS 102)
10 yearsmaximum goodwill life under FRS 102 where it cannot be reliably estimated
78%of the worked example's £40M price allocated to identified intangibles
★ Key Takeaway
PPA decides what the acquirer says it bought. A thorough PPA identifies and values each intangible asset separately, so goodwill is a genuine residual rather than a catch-all. A thin one leaves customer relationships, technology and brands buried in goodwill, where they cannot be tracked, amortised on their own lives or explained to a board.
The PPA Process: Step by Step
Step 1: Determine the total consideration
Calculate the acquisition-date fair value of all consideration transferred: cash, shares, deferred consideration, contingent consideration (earn-outs), and any previously held equity interests.
Step 2: Identify and value tangible assets and liabilities
Start from the target's net assets at book value, then measure each tangible asset (property, equipment, inventory, receivables) and liability (debt, payables, deferred revenue, provisions) at fair value on the acquisition date. For many working-capital items book value approximates fair value; property and deferred revenue often do not.
Step 3: Identify intangible assets
Catalogue every intangible asset that meets the recognition criteria. Under IFRS 3 and ASC 805 an intangible is identifiable if it is separable or arises from contractual or legal rights; FRS 102 requires both unless the acquirer adopts a wider policy. This is the most analytically demanding step and the one that most directly affects the outcome.
Step 5: Recognise deferred tax and calculate goodwill
Recognise a deferred tax liability on the fair value step-ups where the tax base has not moved, then calculate goodwill: total consideration less the fair value of identifiable net assets (tangible and intangible assets, less liabilities including the deferred tax liability).
Step 6: Determine useful lives and amortisation
Assign a useful life to each identified intangible asset and begin amortisation from the acquisition date. Under IFRS, goodwill is not amortised but tested for impairment annually; under FRS 102 it is amortised over its useful life.
Complete Worked Example
A private equity fund's acquisition vehicle buys 100% of the shares of a UK B2B SaaS company for £40.0M. The target reports under FRS 102 and expenses its development costs, so its own balance sheet carries no intangible assets. The buyer's group consolidates under IFRS. All figures are in £M, and each table feeds the next one exactly.
Step 1: Total consideration
Component
Amount (£M)
Cash paid at completion
38.0
Deferred consideration (12 months, at fair value)
1.0
Contingent consideration (earn-out, at fair value)
Trade receivables (credit risk on two overdue accounts)
2.8
2.7
(0.1)
Deferred revenue (cost to fulfil plus a normal margin)
(2.0)
(1.5)
0.5
Net working-capital step-up
0.4
The deferred revenue adjustment reflects the fact that the acquirer inherits an obligation to deliver the service but not the selling costs already incurred to win it. IFRS 3 measures the obligation at fair value, typically the cost to fulfil plus a normal profit margin, which is below the contractual amount. US GAAP now differs here: since ASU 2021-08, ASC 805 measures acquired contract liabilities under ASC 606 as if the acquirer had originated the contracts, so a US GAAP allocation would usually keep the £2.0M.
Step 4: Fair value step-ups on intangible assets
None of these assets is on the target's balance sheet, so each fair value is also its step-up.
Intangible asset
Method
Key assumptions
Fair value = step-up (£M)
Customer relationships (400 enterprise clients)
MPEEM
10% annual attrition, contributory charges for platform, brand, workforce and working capital, 15% discount rate
15.8
Developed technology (SaaS platform)
RFR
12% royalty on platform revenue, 6-year life with 15% a year technical decay, 15% discount rate
6.9
Brand and trade name
RFR
3% royalty on £18M revenue growing 8% a year, 10-year life, 13% discount rate
3.4
Order backlog
MPEEM
£4.2M contracted but unbilled revenue delivered over 6 months, net of fulfilment costs and contributory charges
1.8
Proprietary data assets
Cost approach
Replacement cost of assembling and cleansing the dataset, less obsolescence
Cash flows with and without a 3-year covenant, weighted for a 40% likelihood that the founders would compete
0.7
Total identified intangible assets
31.2
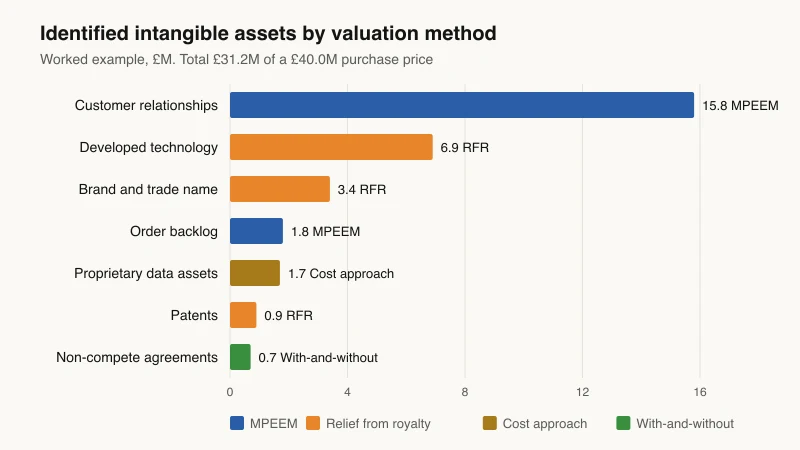
Identified intangible assets in the worked example, by valuation method (£M). Customer relationships valued by MPEEM carry half the total.
The methods follow the asset. Relief from royalty suits assets that could plausibly be licensed (brand, technology, patents). MPEEM suits the asset that drives the cash flows of the whole business, here the customer relationships, and the backlog that sits alongside them. With-and-without suits an asset whose value is the loss it prevents, which is what a non-compete does. Our guide to choosing between RFR and MPEEM covers the trade-offs in more depth.
⚠ Warning
Check for double counting before adding the column up. Here the customer relationship MPEEM excludes the backlog cash flows, which are valued separately, and the patents protect a data-matching process licensed apart from the platform, so their royalty does not overlap the technology RFR. An allocation that counts the same revenue twice overstates the intangibles and understates goodwill.
Step 5: Deferred tax on the step-ups
Because the buyer acquired shares, the target's tax bases do not change. The intangibles keep a tax base of nil and the working-capital items keep their old tax bases, so every step-up is a temporary difference under IAS 12 (FRS 102 Section 29 and ASC 740 work the same way).
Component
Amount (£M)
Intangible asset step-ups
31.2
Working-capital step-ups
0.4
Total temporary differences (net)
31.6
Deferred tax liability at 25%
7.9
The 25% is the UK main rate of corporation tax, the rate expected to apply when the differences reverse. No deferred tax is recognised on the goodwill itself.
Step 6: Goodwill
Component
Amount (£M)
Total consideration
40.0
Less: net assets at book value
(3.3)
Less: working-capital step-ups
(0.4)
Less: intangible asset step-ups
(31.2)
Add: deferred tax liability
7.9
Goodwill
13.0
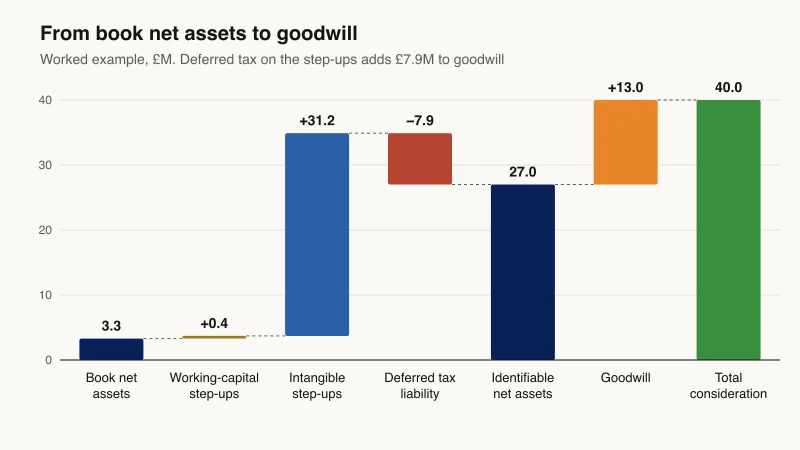
Put the other way round, the identifiable net assets at fair value are £27.0M (3.3 + 0.4 + 31.2 − 7.9), and goodwill is the £13.0M by which the £40.0M price exceeds them. The interactive walk-through above enters the same figures, with net tangible assets after deferred tax as (4.2): 3.3 + 0.4 − 7.9.
From book net assets to goodwill: the worked example's £40.0M consideration, bridged (£M).
Goodwill is 32.5% of the price, but £7.9M of it is the mirror image of the deferred tax liability: without that liability, goodwill would be £5.1M, or 12.75% of the price. That £5.1M is the economic residual: the assembled workforce of 150 employees (which IFRS 3 does not allow to be recognised separately), expected synergies from selling into the buyer's existing client base, and the going-concern value of the business.
★ Key Takeaway
In a share purchase, deferred tax on the step-ups adds to goodwill pound for pound. Before comparing goodwill across deals, or judging whether an allocation identified enough intangibles, separate the deferred tax gross-up from the economic residual.
PPA Accounting: The Journal Entries
PPA accounting records an acquisition in two places: the parent records its investment at the consideration paid, and on consolidation that investment is replaced by the acquiree's assets and liabilities at fair value, a deferred tax liability on the step-ups, and goodwill as the balancing figure. The entries below use the worked example.
Entry 1: Parent's own accounts, acquisition date
Account
Dr (£M)
Cr (£M)
Investment in subsidiary
40.0
Cash
38.0
Deferred consideration (liability)
1.0
Contingent consideration (liability)
1.0
Transaction costs are left out: IFRS 3 and ASC 805 expense them, while FRS 102 adds directly attributable costs to the cost of the combination.
Entry 2: Consolidation, acquisition date
Account
Dr (£M)
Cr (£M)
Share capital and reserves of the target (pre-acquisition)
3.3
Customer relationships
15.8
Developed technology
6.9
Brand and trade name
3.4
Order backlog
1.8
Proprietary data assets
1.7
Patents
0.9
Non-compete agreements
0.7
Deferred revenue (fair value adjustment)
0.5
Goodwill
13.0
Trade receivables (credit-risk adjustment)
0.1
Deferred tax liability
7.9
Investment in subsidiary
40.0
Total
48.0
48.0
The target's own FRS 102 accounts are untouched. Neither FRS 102 nor IFRS provides for push-down accounting, so the intangibles, the deferred tax liability and the goodwill appear only in the consolidated accounts, which the parent files at Companies House.
Entry 3: Each year after acquisition
Each intangible is amortised over its useful life, and the deferred tax liability unwinds with it. For the customer relationships over 12 years (figures rounded):
Account
Dr (£M)
Cr (£M)
Amortisation expense
1.32
Accumulated amortisation: customer relationships
1.32
Deferred tax liability
0.33
Deferred tax credit (income statement)
0.33
✔ Example
The order backlog (£1.8M) is fully amortised within six months, so it weighs on first-year earnings far more than its size suggests. Under FRS 102 the group would also amortise the £13.0M of goodwill, £1.3M a year if a 10-year life were used, with no deferred tax effect; under IFRS there is no goodwill charge unless an impairment test fails.
Deferred Tax on PPA
The deferred tax liability is the most frequently mishandled line in a PPA. It arises whenever assets are recognised at fair value in the consolidated accounts while their tax base stays where it was, which is the normal position in a share purchase. For intangibles that the target generated internally, the tax base is usually nil, so the whole fair value is a taxable temporary difference.
Recognising the liability reduces the identifiable net assets and increases goodwill by the same amount, as Step 6 showed. The liability then unwinds through the income statement as the intangibles are amortised, which partly offsets the amortisation charge in reported post-tax earnings.
⚠ Warning
Failing to recognise the deferred tax liability on PPA intangible assets is a common error. It understates both goodwill and the liabilities on the post-acquisition balance sheet, and auditors will require the adjustment.
Tax Structure and the Tax Amortisation Benefit
The structure of the deal decides whether the step-ups have any tax effect at all. The points below describe the accounting consequences in the UK; they are not tax advice, and the tax treatment of any deal depends on its facts.
Share purchase vs asset purchase in the UK
Structure (UK)
Tax base of acquired intangibles
Deferred tax in the PPA
Tax relief on amortisation
Share purchase
Unchanged (usually nil for internally generated intangibles)
Liability on the full step-up
None on the consolidation step-ups
Asset (trade and assets) purchase
Broadly the price allocated, under the corporate intangibles rules in Part 8 of the Corporation Tax Act 2009
Little or none
Generally available, following the amortisation in the accounts; goodwill and customer-related intangibles get relief only when bought with qualifying IP, at 6.5% a year (since April 2019)
The tax amortisation benefit (TAB) is a separate, valuation question. Valuers commonly include a TAB in income-approach fair values, because fair value assumes a hypothetical sale of the asset on its own to a market participant, whatever the actual deal structure. Whether to include it, and on what tax life, is a judgement the auditor will expect to see explained.
ℹ Note
A PPA does not create tax relief. Structure does. Take tax advice on structure before signing; the PPA then records the consequences.
IFRS 3 vs ASC 805 vs FRS 102: How the Framework Changes the PPA
The three frameworks share one approach, which IFRS 3 and ASC 805 call the acquisition method and FRS 102 the purchase method: identify the acquirer, measure the consideration and the identifiable net assets at fair value, and treat the residual as goodwill. They differ on which intangibles must be recognised and on what happens to goodwill afterwards.
How the three frameworks treat a purchase price allocation
Topic
IFRS 3
ASC 805 (US GAAP)
FRS 102 Section 19 (UK and Ireland)
Separate recognition of intangibles
Separable or contractual-legal
Separable or contractual-legal; private companies may elect (ASU 2014-18) to subsume customer-related intangibles that cannot be sold or licensed independently, and non-competes, into goodwill
Required only when separable and contractual-legal (18.8); a policy may recognise those meeting one test, applied to the whole class
Goodwill after acquisition
Not amortised; annual impairment test (IAS 36)
Not amortised; impairment test (ASC 350); private companies may elect straight-line amortisation over up to 10 years (ASU 2014-02)
Amortised over its useful life; no more than 10 years if the life cannot be reliably estimated (19.23)
Transaction costs
Expensed
Expensed
Included in the cost of the combination
Contingent consideration
Fair value; a liability is remeasured through profit or loss
Fair value; a liability is remeasured through earnings
Included when payment is probable and can be measured reliably; later revisions adjust goodwill
Non-controlling interest
Fair value or proportionate share of net assets
Fair value
Proportionate share of net assets
Negative goodwill
Gain in profit or loss after reassessment
Gain in earnings after reassessment
Shown below goodwill and released to profit or loss as the non-monetary assets are recovered
Measurement period
Up to 12 months
Up to 12 months
Up to 12 months
✔ Example
Run the worked example under the other frameworks. Under FRS 102 the non-compete agreements (contractual but not separable) would typically fall into goodwill unless the group's policy recognises that class, the customer relationships would stay separate only if they pass both tests, and goodwill would be amortised. Under the US private-company alternative, the customer relationships, order backlog and non-compete agreements, £18.3M of the £31.2M, would typically be subsumed into goodwill, which would then be amortised over no more than 10 years. Same deal, same price, a different balance sheet.
What changed in FRS 102 from 1 January 2026
The FRC's Periodic Review 2024 amendments apply to accounting periods beginning on or after 1 January 2026. Two changes touch a PPA. Section 19 now carries IFRS 3-based guidance on identifying the acquirer (including newly formed entities and reverse acquisitions) and on separating contingent consideration from pay for post-combination services, with new disclosures about contingent consideration; these apply prospectively. And fair value guidance now sits in a new Section 2A, based on the principles of IFRS 13.
What did not change matters as much: goodwill is still amortised, with the 10-year cap where its life cannot be reliably estimated, and the 18.8 recognition test for intangibles in a business combination still requires both separability and contractual-legal rights unless the wider policy is chosen. Our comparison of IAS 38 and FRS 102 Section 18 sets out the wider changes.
For a UK acquirer, the framework usually follows the group. Listed groups consolidate under UK-adopted IFRS; most private equity portfolio groups report under FRS 102. The same deal can therefore produce a different set of recognised intangibles, a different goodwill figure and a different earnings profile depending on where the accounts are prepared. The IFRS 3 vs ASC 805 comparison goes through the transatlantic differences paragraph by paragraph.
Common PPA Mistakes
Having led or reviewed hundreds of purchase price allocations, I see these errors repeatedly:
Under-identifying intangible assets: recognising only 2-3 assets when 8-10 exist, inflating goodwill unnecessarily
Starting too late: beginning the PPA after completion rather than in parallel with due diligence
Using company WACC for all assets: different intangible assets carry different risk profiles and should have different discount rates
Ignoring the TAB: leaving it out of income-approach values without explaining why
Treating all customer relationships as one asset: contractual and non-contractual relationships have different profiles and should be valued separately
Compressing useful lives: choosing shorter lives to reduce balance sheet exposure, at the expense of economic accuracy
Forgetting contingent consideration: earn-outs and contingent payments must be included at fair value in the total consideration
Leaving out the deferred tax liability: understating goodwill and liabilities in a share purchase
Applying the wrong framework's recognition test: using the IFRS 3 test in an FRS 102 allocation, or the reverse, changes which intangibles reach the balance sheet
The Measurement Period
IFRS 3 allows a measurement period of up to 12 months from the acquisition date to finalise the PPA; ASC 805 and FRS 102 allow the same. During this period, the acquirer can adjust the provisional values assigned to assets and liabilities as new information about conditions at the acquisition date emerges. Under IFRS 3 and FRS 102, adjustments during the measurement period are made retrospectively, as if the revised values had been recognised on the acquisition date; under ASC 805 (since ASU 2015-16) they are recognised in the period in which they are determined, without restating comparatives. See also how long a purchase price allocation takes.
After the measurement period closes, adjustments to the PPA are permitted only to correct errors (under IAS 8 for IFRS reporters), not to refine estimates.
The acquirer's finance team: provides the financial data, transaction details, and business context
External valuation specialists: typically Big Four firms or specialist valuation practices; they perform the technical valuation work
The acquirer's auditors: review the PPA and may challenge assumptions, methods, and conclusions
Tax advisers: advise on deal structure and its tax consequences
Legal counsel: advises on IP ownership, contract transferability, and regulatory asset status
For mid-market transactions (£10M-£100M), the PPA typically costs £30K-£100K, a modest sum relative to the amounts it puts on the balance sheet. For larger transactions, costs scale with the number of assets and jurisdictions.
PPA Best Practice
Practices that make a PPA defensible
Practice
Benefit
Start PPA planning during due diligence
Better asset identification, more time for valuation
Engage specialist valuers early
Access to licensing databases, comparable transactions
Document all assumptions
Audit readiness, defensibility
Perform sensitivity analysis
Understand the impact of key assumption changes
Reconcile the total to the purchase price
Confirms that goodwill is explainable and reasonable
Take tax advice on structure before signing
Share or asset purchase changes the tax base and the deferred tax
★ Key Takeaway
The PPA is not a compliance afterthought. A well-executed PPA gives the acquirer a clear, defensible account of exactly what it bought, sets amortisation on realistic lives, and leaves a goodwill figure that can be explained to a board and an auditor. Start planning before the deal closes.
Frequently Asked Questions
What is purchase price allocation in simple terms?
It is the process of splitting the price paid for a business across everything identifiable that came with it: tangible assets, liabilities and intangible assets such as customer relationships, brands and technology, each at fair value. Whatever cannot be attributed to an identifiable item is goodwill.
How is goodwill calculated in a purchase price allocation?
Goodwill is the total consideration less the fair value of the identifiable net assets, including the deferred tax liability on the step-ups. In the worked example above, £40.0M less £27.0M of identifiable net assets leaves £13.0M of goodwill. Our guide on how to calculate goodwill covers partial and full goodwill.
What journal entries does PPA accounting require?
The parent debits its investment and credits cash and any deferred or contingent consideration. On consolidation, the investment and the target's pre-acquisition equity are eliminated, the fair value step-ups and the deferred tax liability are recognised, and goodwill is the balancing debit. Amortisation and the matching unwind of the deferred tax liability follow each year.
Is a purchase price allocation required under FRS 102?
Yes. Section 19 of FRS 102 requires the purchase method for business combinations other than group reconstructions, which may use merger accounting, so a UK group reporting under FRS 102 allocates the cost of the combination to identifiable assets, liabilities and contingent liabilities, with the residual as goodwill. Fewer intangibles are typically recognised separately than under IFRS 3, and goodwill is amortised.
Does a PPA change the acquired company's own accounts?
Not in the UK. The fair value step-ups, the deferred tax liability and the goodwill are recognised in the acquirer's consolidated accounts; the subsidiary's own FRS 102 or IFRS accounts continue on their existing carrying amounts.
Resources
Value the assets: the Asset Valuator in Opagio Intangibles values intangible assets with RFR, MPEEM, with-and-without and the cost approach
Tony Hillier is Chairman of Opagio with 30 years of experience in structured finance, M&A advisory, and asset valuation. He has led purchase price allocations across technology, financial services, professional services, and managed services sectors, with deal values from £5M to £500M. Meet the team.
Share:
TH
Tony Hillier — Chairman, Co-Founder
MA, Balliol College, University of Oxford | Harvard Business School MBA with Distinction
See how Opagio Intangibles values your full asset portfolio
Opagio Intangibles runs RFR, MPEEM, With & Without and Cost across every intangible asset you own — the evidence base that survives Fair Value scrutiny.
How to value in-process research and development (IPR&D) in purchase price allocations under IFRS 3 and ASC 805. Covers probability-adjusted cash flow modelling, completion risk assessment, and the critical accounting differences between standards.
How to value non-compete agreements using the With-and-Without method in purchase price allocations. Covers the conceptual framework, scenario modelling, probability weighting, and enforceability considerations.
A step-by-step guide to recognising and measuring intangible assets under IFRS 3 Business Combinations. Covers the identification criteria, fair value measurement, and purchase price allocation process with practical examples.
Get the latest insights on intangible asset growth and productivity delivered to your inbox.
We use essential cookies to make our website work. We'd also like to use analytics cookies to improve your experience. You can manage your preferences at any time.
Cookie Policy