How Much Is My Business Worth? What a Buyer Will Pay
By Ivan Gowan· 2026-07-05how much is my business worthwhat is my business worthvalue my businessbusiness valuationexitintangible assets
Your business is worth a multiple of its normalised earnings: the profit it makes on a sustainable, owner-independent basis, multiplied by a figure a buyer chooses. The earnings are largely fixed by the time you go to market; the multiple is not, and a buyer sets it by judging how much of those earnings will survive without you. That judgement rests mostly on intangible assets your accounts never show, so the honest answer to "how much is my business worth?" is a range you can narrow with evidence, not a number a calculator can read off your turnover.
Last reviewed: October 2026. Written for UK owner-managed businesses; accounting references are to FRS 102, with IAS 38 alongside for groups reporting under IFRS.
EV = E × Menterprise value is normalised earnings times a multiple
1 turnof the multiple adds a full year's earnings to the price
EV − net debtthe bridge from enterprise value to the equity value you are paid
Ask most owners what their business is worth and the answer traces back to a rule of thumb: "three or four times profit", something a peer sold for, or a figure an accountant mentioned in passing. Ask a buyer and you get a different answer. A buyer does not value your accounts. They value a stream of earnings they expect to continue after you have gone, and they set the price by applying a multiple to it.
This guide is for owners of UK businesses turning over roughly £1m to £100m who want to know what the business would sell for. It covers the earnings figure a buyer starts from, the multiple they apply, the levers that move that multiple, and what an online business valuation calculator can and cannot tell you. It is seller-at-exit framing: how a trade or private equity buyer prices the whole business you are selling. Valuing a business to raise a funding round is a different exercise, and the full set of valuation methods is a subject of its own: see how to value a business.
How much is my business worth? The short answer
Almost every private company sale reduces to one equation.
📚 Definition
Enterprise value = normalised earnings × multiple. The buyer agrees a sustainable earnings figure, applies a multiple to it, and then bridges from enterprise value to the equity value paid for your shares.
Enterprise value is the value of the business itself, before considering how it is financed. UK deals are usually priced on a cash-free, debt-free basis: from the enterprise value the buyer deducts borrowings, adds surplus cash and adjusts for a normal level of working capital to reach the equity value, the figure paid for your shares. The number that gets negotiated, and the one everything turns on, is enterprise value, and it has two inputs.
The earnings figure is usually EBITDA (earnings before interest, tax, depreciation and amortisation), because it strips out financing and accounting choices and approximates the cash the business generates. Smaller businesses are sometimes valued on adjusted operating profit or on the owner's discretionary earnings, but the principle is the same: settle on a sustainable earnings number, then apply an EBITDA multiple.
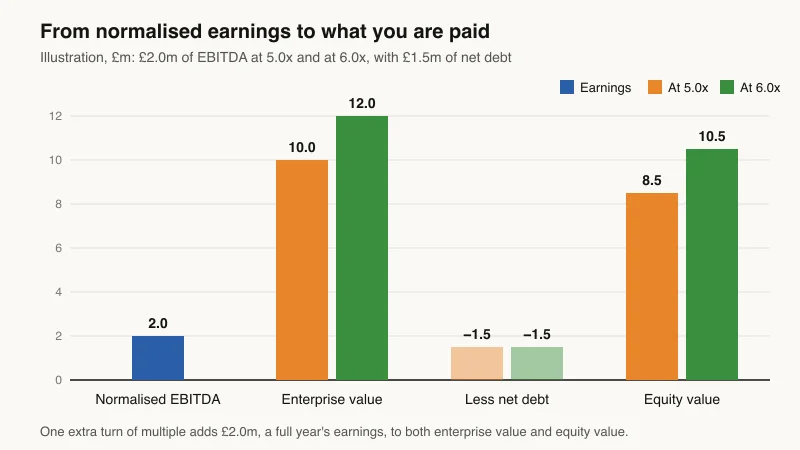
Illustration: from normalised earnings to the equity value a seller receives (£m). One extra turn of multiple on £2.0m of earnings adds £2.0m.
The gap between the orange and green bars is the point owners most often miss. On a business earning £2m, moving the multiple from 5x to 6x adds £2m of enterprise value, a full year's earnings. To add the same £2m through earnings alone at 5x, the business would need to make £400,000 more every year, a 20% rise in profit. Earnings are largely set by the time you go to market. The multiple is still in play, which is why a well-prepared seller concentrates on it.
The two numbers that decide what your business is worth
Input
What it is
Who sets it
How much you can move it before a sale
Normalised earnings
Sustainable, owner-independent EBITDA
Agreed with the buyer in diligence
Modestly: mostly by trading better and adjusting cleanly
The multiple
Turns of earnings the buyer will pay
Set by the buyer's read of risk, growth and quality
Substantially: this is where preparation pays
Price is what you get, value is what it's worth
The first distinction to fix is the one between price and value, because confusing them costs owners money.
Value is an analytical estimate: what the business is worth on a defensible basis, derived from its earnings, its assets and its risk. Price is what a specific buyer, on a specific day, in a specific process, agrees to pay. Value sets the anchor; price is where negotiation, competition and deal structure land relative to it.
★ Key Takeaway
You cannot negotiate your way to a good price from a weak value. The multiple a buyer offers is a verdict on how much of your business survives without you, and that verdict is formed long before anyone sits down to negotiate. Preparation moves value; tactics only move price around it.
Two businesses with identical profit can command very different prices. The one with contracted, recurring revenue, a team that runs it and registered intellectual property is worth more to a buyer than the one that depends on the founder's personal relationships, even though the profit and loss statement looks the same. The difference is not in the numbers a buyer can see. It is in the assets underneath them.
Step one: normalised earnings, the base of what your business is worth
The profit in your statutory accounts is almost never the profit a buyer values. Owner-managed businesses are run to be tax-efficient and to suit the owner, not to present a clean earnings picture to an acquirer. So a buyer normalises: they rebuild your earnings to show what the business would produce under normal ownership. Normalisation adds back and strips out a defined set of items.
Owner's remuneration and benefits
If you pay yourself above or below a market rate for the role, a buyer adjusts to what it would cost to employ a manager to do your job. The car, family members on the payroll and personal expenses run through the business are all normalised out.
One-off and non-recurring items
A bad-debt write-off, a legal dispute, a relocation, a grant: anything that will not repeat is stripped out so the earnings reflect the ongoing business, not an unusual year.
Non-trading and discretionary costs
Charitable giving, sponsorships, an office that suits the owner rather than the business: a buyer removes spend that a new owner would not necessarily continue.
Related-party and off-market arrangements
Rent paid to a property you own and purchases from a connected company are re-based to market terms, so the earnings are not flattered or depressed by arrangements a buyer cannot replicate.
The output is your normalised EBITDA, the base the multiple is applied to and the most important financial number in the transaction. Get it right and you are paid a multiple on the real earnings power of the business. Leave a genuine add-back on the table, or claim one you cannot evidence, and you either give value away or hand the buyer a reason to distrust everything else you present.
ℹ Note
Normalisation is not creative accounting. Every adjustment must be defensible with documentation a buyer's advisers can verify. An add-back you can prove strengthens your position; one you assert but cannot support invites a discount on the whole number. Our normalised EBITDA guide sets out each adjustment, which way it goes and a worked EBITDA bridge.
Because the base earnings are multiplied, an error here is amplified. At 6x, a £100,000 add-back you fail to substantiate is £600,000 of enterprise value lost. The owners who defend their price arrive with a normalised profit and loss statement already built: not a claim to be argued, but a reconciled document a buyer can check line by line.
Step two: the multiple a buyer will pay
There is no single multiple for your sector, and there is no table that tells you what your business is worth. A buyer starts from a rough range for businesses of your size and type, then moves up or down that range on what diligence shows them. Two features of the UK market for owner-managed businesses are worth knowing before you hear a number.
First, size matters. Smaller owner-managed businesses tend to be priced on lower multiples than larger businesses with a management team, recurring revenue and a record of growth, because more of a small business's earnings depend on one or two people and a few customers. The gap between the two ends of the range can be several turns of earnings, which on the arithmetic above is several years of profit.
Second, headline figures mislead. Published indices of UK private-company deal multiples, such as BDO's Private Company Price Index, are a useful sense check on market conditions, but they are built from completed deals where enough was publicly disclosed to calculate the multiple, which tends to mean larger deals. A rule of thumb from a broker, or a multiple a peer achieved, says little about where your business sits until the buyer's questions below have been answered.
Illustrative only: where a UK owner-managed business tends to sit in its range
Position in the range
What the buyer sees
Typical profile
Lower end
Earnings that depend on the owner and a few customers
Founder holds the key relationships; project revenue re-won each year; little documented
Middle
Earnings a new owner can underwrite with some protection
Second tier of management in place; a mix of repeat and contracted revenue; some concentration
Upper end
Earnings that will continue after completion
Business runs without the owner; contracted, recurring revenue; diversified customers; registered IP; growth evidenced
The range itself moves with the market (interest rates, buyer appetite, sector sentiment), and you do not control that. Where you sit inside it is the part you do control, and it is decided by the quality of your earnings.
Quality of earnings: how good, not just how much
Once a buyer knows how much the business earns, they ask how good those earnings are. This is the quality of earnings review, and it is where the multiple is really set. Two businesses with the same normalised EBITDA are not worth the same if one earns it from long-dated contracts and the other from a handful of relationships that could leave.
What a quality of earnings review asks
Question
Supports a higher multiple
Pulls the multiple down
Are the earnings recurring?
Contracted, subscription or repeat revenue
Project or one-off revenue that must be re-won
Are they diversified?
No customer large enough to hurt if it left
One or two customers carry the business
Are they cash-backed?
Profit that converts cleanly to cash
Profit tied up in slow debtors or growing stock
Which way are they moving?
A rising earnings line
Flat or declining earnings, priced for the trend
Do they depend on the owner?
Relationships and decisions sit with the team
Earnings a buyer believes leave with the founder
⚠ Warning
Owners routinely over-value headline profit and under-value its quality. A business earning £1.5m from three hundred contracted customers on annual renewals is worth materially more than one earning £1.5m from twelve handshake relationships, whatever the statutory accounts say. If your revenue is stickier than it looks on paper, the work before a sale is to prove it; if it is lumpier than it looks, that is the risk to fix first.
What moves the multiple: four levers a seller controls
Follow the questions a quality of earnings review asks and you find they are not really financial questions. They are questions about assets that never appear on the balance sheet. Four of them do most of the work.
Owner dependency
Owner dependency is the most common reason a strong-looking business attracts a weak offer. If the business cannot be shown to run without you, the buyer is not acquiring a company; they are acquiring a job, and they price it accordingly, through a lower multiple, a longer handover or more of the price deferred into an earn-out. The fix takes time: documented processes, a second tier of management, and customer relationships held by the team rather than by you. Our guide on how to reduce founder dependency sets out the steps, and the glossary entry on key person risk explains how buyers test for it.
Recurring revenue
A buyer underwrites recurring revenue with far more confidence than revenue that must be won again each year. Contracts, subscriptions, framework agreements and evidenced repeat purchasing all count, provided you can show them: renewal histories, retention rates by cohort, and contracts that survive a change of ownership.
Customer concentration
A common rule of thumb is that buyers start asking questions once a single customer passes about 10% of revenue, and price the risk more heavily as that share rises. Concentration is rarely fixed by losing the large customer. It is fixed by growing the rest of the book, by contracting the large relationship on terms that survive a sale, and by evidencing how long it has lasted.
Intangible assets
Brand, customer relationships, technology, data and know-how are what a buyer is really paying for, and each pushes the multiple in the same direction: the more of your value is documented, owned and transferable, the higher the number. At Opagio we organise these assets through the Opagio 12 framework, twelve categories of intangible value driver. Working through them is how a seller finds the value the accounts miss and pre-empts the risks a buyer would otherwise use to reduce the price.
How the Opagio 12 drivers move the multiple
Opagio 12 driver
What a buyer is really pricing
Effect on the multiple
Brand & Reputation
Whether your name and standing transfer to the new owner
Up when the brand is owned and recognised beyond the founder
Customer Capital
Contracted, recurring, low-churn revenue they can underwrite
Up with stickiness; down with concentration
Technology & Innovation
Proprietary systems and IP they cannot easily rebuild
Up when owned outright and defensible
Human Capital
Whose knowledge walks out of the door at completion
Down when critical know-how sits only with the owner
Organisational Capital
Documented processes: a business that runs without you
Up when it demonstrably operates without the founder
Content & IP
Owned content, trade marks and registered rights
Up when title is clean and registrations are current
Ecosystem & Partnerships
Transferable supplier, channel and partner relationships
Up when they survive the change of ownership
Switching Costs & Lock-In
How hard it is for customers to leave
Up when lock-in is genuine and evidenced
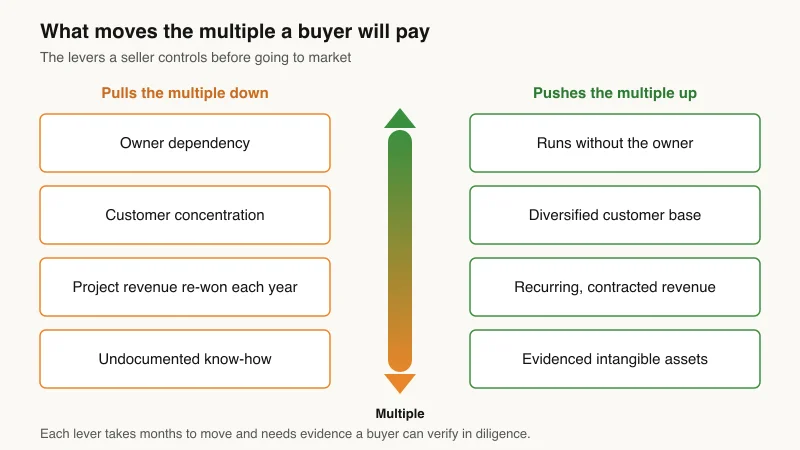
The levers a seller controls: what pushes a buyer's multiple up, and what pulls it down.
The multiple movers
Moves the multiple up
Moves the multiple down
Recurring, contracted revenue
Project revenue that must be re-won each year
Diversified customer base
One customer carrying a large share of revenue
Business runs without the owner
Founder holds the key relationships and decisions
Documented processes and systems
Knowledge that lives only in people's heads
Registered IP with clean title
Unregistered marks, unclear ownership of technology
Growing earnings
Flat or declining earnings
Clean, cash-backed profit
Earnings that do not convert to cash
Strong management team staying on
Business that depends on the seller staying
Behind most of this list sits evidence: the difference between a claim a buyer must take on trust and a fact they can verify. Each lever takes months to shift, which is why the multiple is won in the year or two before a sale, not in the final negotiation. For a deeper look at the mechanism, read how intangibles affect your exit multiple.
✔ Example
Consider an owner who spends eighteen months distributing customer relationships across a team, documenting the delivery process and registering the trade marks, and goes to market with an Opagio Value Drivers Register that lists each asset and the evidence behind it. When the buyer's diligence questions whether the revenue is really recurring, the contracts and retention data are already in the data room. The multiple holds, and the competitive tension the evidence creates gives the seller room to push for the upper end of the range.
Why most of the value is invisible on your balance sheet
For most service, technology and brand-led businesses, the larger part of what a buyer pays for is intangible: brand, customer relationships, technology, data, processes and know-how. Yet little of it appears on your balance sheet. Under FRS 102, as under IAS 38, internally generated brands, customer lists and similar items cannot be recognised as assets; their cost is expensed as it is incurred. Only narrow categories, such as development costs that meet the standards' conditions, can be capitalised.
This is a well-established accounting rule, not a flaw to be fixed. But it has a consequence a seller must understand: the balance sheet a buyer receives understates what the business is worth, and the gap is the value you are selling. A buyer knows this. Their diligence is built to find, test and price the intangible assets your accounts omit. The question is whether you have identified and evidenced those assets before they do, or whether you let their advisers set the narrative.
★ Key Takeaway
Net assets are not the answer to "what is my business worth?" for most owner-managed businesses. The accounts record what the business cost to build; a buyer pays for what it will earn, and that is decided by assets the accounts were never designed to show.
Can a business valuation calculator tell me what my business is worth?
Searching "value my business" turns up plenty of online calculators that ask for your turnover and profit and return a figure. They can be a starting point for a conversation, but they cannot answer the question a buyer will ask, for two reasons. They work from reported profit, not normalised earnings, so the base is wrong before any multiple is applied. And they apply a generic multiple for your sector, which ignores everything in the sections above: owner dependency, recurring revenue, concentration and the quality of your intangible assets. Those are exactly what move a real multiple by several turns.
That is why we do not offer an instant figure for the whole business. A £ value is only as defensible as the inputs behind it, and a figure built on unadjusted profit and a sector average is not one a buyer will accept. What the free tools at Opagio do instead is narrower, and each is honest about its scope. When you need a formal figure, for a shareholder exit, a tax return or a dispute, that is the job of an independent business valuation report.
An indicative estimate for one intangible asset, such as a brand or a piece of technology, built on a published median royalty rate and fixed default assumptions after a short form and email verification
A formal valuation, a value for the business, or a value for more than one asset
A short self-assessment that scores your business across the Opagio 12 value drivers against sector medians and shows where hidden value is likely to sit
A £ figure of any kind
⚠ Warning
Treat any single £ figure from an online calculator with caution, including in negotiation. A buyer will rebuild your earnings and set the multiple on their own diligence; a number that has not been through that process anchors expectations without defending them.
How a buyer allocates the price across your assets
Once a price is agreed, an acquiring company does not record it as a single sum. Under the accounting rules for business combinations, the buyer spreads the purchase price across the individual assets acquired: the tangible ones and the identifiable intangibles, such as brand, customer relationships, technology and contracts. Whatever cannot be attributed to a specific asset is booked as goodwill. For the mechanics, see our guide on how buyers allocate the purchase price.
That allocation previews how a buyer sees the shape of your value: which assets carry the weight, and which are effectively unpriced because you never identified them. The structure of the payment matters too. Buyers rarely pay the whole price in cash at completion; part is often held back as deferred consideration or tied to future performance through an earn-out, so the headline figure and the cash you receive can differ. In the UK, whether the deal is a share sale or an asset sale also changes the tax position for both sides, including the reliefs available to you as a seller; see share sale vs asset sale in the UK and take advice from a UK tax adviser before heads of terms.
See what a buyer's diligence will find, before they do
Opagio Intangibles builds the evidence a buyer will test. It identifies and classifies your intangible assets across Opagio 12, values them with recognised methods, and produces the Opagio Value Drivers Register and a Normalised P&L: the documents that turn the value you claim into a case a buyer can verify. See how Opagio prepares a business for sale.
Frequently Asked Questions
How much is my business worth?
For most UK owner-managed businesses, a buyer values the business as a multiple of its normalised earnings, usually EBITDA after adjusting for owner costs and one-off items. The multiple depends on how much of those earnings will continue without you, which turns on recurring revenue, customer concentration, owner dependency and the quality of your intangible assets. Net debt is then deducted to reach the equity value you are paid.
What multiple will a buyer pay for a UK small business?
There is no fixed multiple. Smaller owner-managed businesses tend to sell on lower multiples than larger ones with a management team, contracted revenue and a record of growth, and the gap can be several turns of earnings. Published indices of UK private-company deals are a sense check, but they skew towards larger, disclosed transactions. Where your business sits is decided in diligence.
Is my business worth more than my accounts say?
Often, yes. UK accounting standards do not let a business recognise internally generated brands, customer relationships or know-how as assets, so the balance sheet understates what a buyer pays for. The value shows up in the multiple instead, provided you can evidence those assets before a buyer's diligence looks for them.
Can an online business valuation calculator tell me what my business is worth?
Only roughly. Most calculators apply a sector-average multiple to reported profit, which skips normalisation and ignores the factors that move a real multiple. They can start a conversation, but a buyer will rebuild your earnings and set their own multiple. Use the result as a prompt for preparation, not as an asking price.
How can I increase what my business is worth before I sell?
Start twelve to twenty-four months out. Reduce your own role in sales and delivery, document processes, grow recurring and contracted revenue, reduce reliance on your largest customers, register and secure your intellectual property, and build a normalised profit and loss statement you can evidence line by line. Each step supports a higher multiple, and none can be rushed in the final months.
Putting the number together
Your business is worth a multiple of its normalised earnings, and the multiple measures how much of that earnings power survives without you. The earnings are largely set by the time you go to market; the multiple is not. It is moved by the intangible assets your accounts do not show: recurring revenue, a business that runs without you, a broad customer base, registered IP and documented processes. Identify and evidence those assets before a buyer's diligence goes looking, and you defend a higher multiple rather than concede one.
Ivan Gowan is Founder and CEO of Opagio. He spent twenty-five years in fintech, including at IG Group, before building Opagio to help owners see and evidence the intangible value in their businesses. Meet the team.
A buyer prices your business through its intangible assets whether they name them or not. Here are the ones that earn a premium in a sale — and how to evidence them before diligence goes looking.
The headline price gets agreed at heads of terms. What you actually keep is decided afterwards, in the earn-out, the warranties and the disclosure letter. Here is how an earn-out is structured, what to negotiate, and when to walk.
A seller wants a share sale. A buyer usually wants an asset sale. The structure you land on decides your tax, your risk and how the intangibles are valued. Here is the UK trade-off.
Get the latest insights on intangible asset growth and productivity delivered to your inbox.
We use essential cookies to make our website work. We'd also like to use analytics cookies to improve your experience. You can manage your preferences at any time.
Cookie Policy