Exit Planning: The 24-Month Plan to Sell Your Business
By Ivan Gowan· 2026-07-05exit planningbusiness exit planningsell your businessbusiness saleexit strategyowner dependencyintangible assets
Exit planning is the work of preparing a business, and its owner, for a sale long before it goes to market: choosing the route and the timing, reducing the business's dependence on the owner, and building the evidence of what it owns and earns that a buyer's diligence will test. For most owners the useful horizon is about twenty-four months, because the issues that cap a sale price take a year or more to fix.
📚 Definition
Exit planning is not the same as an exit strategy. The strategy is the destination: a trade sale, a management buyout, a sale to private equity or a transfer to an employee ownership trust. The exit plan is the programme of work that gets the business to that destination at the best price it can support.
Last reviewed: October 2026. UK framing throughout; tax points are general information, not tax advice.
Most owners begin preparing to sell their business about three months before they go to market. They tidy the accounts, write a short summary, and call a broker. The owners who achieve the strongest outcomes begin closer to twenty-four months out — because the value realised at exit is built in the eighteen months before the business ever reaches a buyer.
This guide sets out a 24-month exit plan: what to do in each six-month window, how to reduce owner dependency, how to run the intangibles workstream alongside the numbers, and how to build the evidence that lets you defend your price rather than concede it. It is written for owners of UK businesses turning over roughly £1m to £100m who are considering an exit.
Why time is the biggest lever on price
A buyer does not pay for last year's profit. They pay a multiple of normalised earnings, and they set that multiple based on how much of your business will survive without you. Time is what lets you improve the answer to that question — and improving it is worth more than any negotiating tactic applied in the final week.
60–80%of a modern business's enterprise value sits in intangible assets
24 monthsthe runway the best-prepared owners give themselves
6–12 monthsa well-run sale process, once you go to market
The reason is straightforward. The things that cap a sale price — customer concentration, undocumented processes, key-person risk, unregistered intellectual property, revenue that turns out to be less recurring than it looked — all take months to fix. You cannot manufacture readiness in the final quarter, and a buyer's diligence is designed to find exactly the weaknesses you left too late to address.
★ Key Takeaway
The multiple a buyer offers is a verdict on how dependent the business is on you. Everything in a good exit plan is really about transferring value out of your head and into the business.
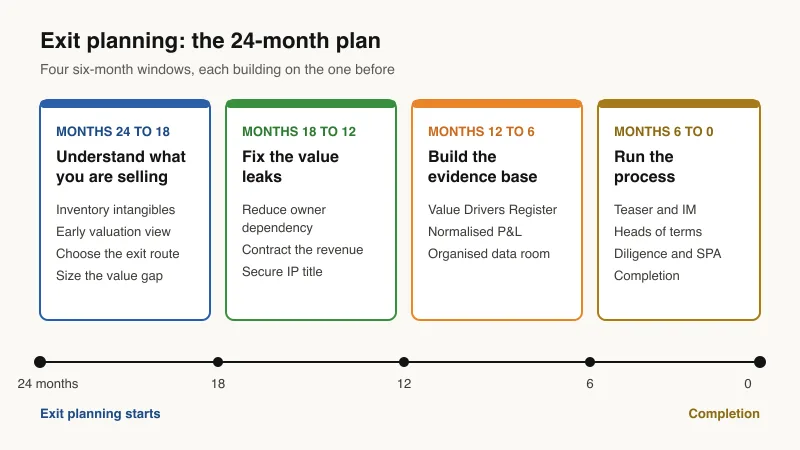
The plan runs in four six-month windows. Each has its own job, and each depends on the one before it.
The 24-month exit plan in four windows. Source: Opagio.
Months 24 to 18: understand what you are selling
The first window is about seeing your business the way a buyer will. That means cataloguing what you actually own — not the assets on your balance sheet, but the intangible assets that produce your earnings: your brand, your customer relationships, your technology and intellectual property, your data, and the processes that make the business run.
Most owners are surprised by this inventory. A business told it is "worth about four times earnings" often turns out to hold dozens of separately identifiable intangible assets — a registered methodology, long-dated contracts, a proprietary delivery process — that a buyer would value individually. Identifying them early tells you where your value concentrates and, just as importantly, where it is exposed.
ℹ Note
The lens for this inventory is the Opagio 12 framework — twelve intangible value drivers that determine hidden enterprise value. Working through them systematically is how you find the value the accounts miss and the risks a buyer will price.
This is also the window to get an early, honest valuation view — not to set a number in stone, but to understand the gap between what you hope to achieve and what the evidence currently supports. That gap is your work list for the next eighteen months.
Months 18 to 12: fix the value leaks
With the inventory in hand, the second window is remediation. You are working through the weaknesses that diligence would otherwise use to chip your price, in rough order of impact.
Reduce founder dependency
Document the decisions and relationships only you hold. Distribute customer contacts across your team. Remove yourself from day-to-day operations in stages so the business demonstrably runs without you.
Strengthen revenue quality
Convert informal arrangements into contracts. Address customer concentration. Evidence retention and recurring revenue, because sticky revenue earns a higher multiple than lumpy revenue.
Protect the intangibles
Register trademarks, confirm you own your technology and content outright, and secure the chain of title on anything a buyer would separately value.
Normalise the numbers
Strip out owner-specific costs and one-offs so a buyer can see the real earnings power. This is your normalised EBITDA, and it is the base your multiple is applied to.
Each of these is a project, not a task, which is why the window is a full year. Founder dependency in particular — the concern captured by the Organisational Capital and Human Capital drivers within the Opagio 12 framework — is the most common reason a strong-looking business attracts a weak offer, and the slowest to fix. The next section sets out what a buyer tests.
⚠ Warning
Do not leave IP registration and contract tidy-ups to the final months. A buyer's lawyers will find unregistered marks and missing assignments, and they will treat each one as either a price reduction or a warranty you must give. Fixing them early removes the ammunition.
Owner dependency: the lever that takes longest to move
Owner dependency is the extent to which a business's earnings rely on its owner personally: their decisions, their knowledge, their relationships and their presence. A buyer is paying for future earnings they will receive after you leave, so every part of the business that only works because you are in the room is a part they will discount, defer into an earn-out, or protect with a tie-in that keeps you working for them after completion.
It is rarely only the founder. The same test applies to anyone whose departure would damage the business: a sales director who holds the three largest accounts, an engineer who is the only person who understands the core system, an operations manager whose know-how has never been written down. Buyers call this key person risk, and in a valuation it shows up as a key person discount or as harder deal terms.
What a buyer tests for owner dependency
Area
The buyer's question
What reduces the dependency
Decisions
Who makes the pricing, hiring and customer calls?
A management team with written authority, visibly making those calls
Relationships held by account teams, under contract with the company
Key people
Who else would the business struggle to lose?
Succession cover, retention arrangements and shared knowledge across the team, its Human Capital
Supplier and partner terms
Do arrangements rest on your personal goodwill?
Written agreements in the company's name that survive a change of control
The work is gradual by design. You document a process, hand over a decision, introduce a colleague to a client and then step back, and repeat that until the evidence shows the business performing without you. A buyer will look for a track record of the business running without you, not a promise that it could, which is why this belongs at the start of an exit plan rather than the end.
★ Key Takeaway
Customer relationships held by the business, processes written down and a team that makes decisions without you are what turn owner dependency from a price discount into a transferable asset. For the step-by-step method, see how to reduce founder dependency before you sell.
Months 12 to 6: build the evidence base
By now the business is stronger. The third window is about proving it. Every claim you make in a sale will be tested, so the owners who defend their price are the ones who arrive with documentation rather than assertion.
Three documents do most of the work: a register of the intangible assets you own and what each is worth; a profit and loss statement normalised so a buyer can see the real earnings; and a data room organised so diligence runs quickly and cleanly. Together they turn a defensive negotiation into a confident one.
Evidence beats assertion
Opagio Intangibles builds this evidence base directly. It identifies and classifies your intangible assets across Opagio 12, values them with recognised methods, and produces the Opagio Value Drivers Register and a Normalised P&L — the documents a broker can put in front of buyers to justify the ask. See what a buyer's diligence will find — book a demo of Opagio Intangibles.
If part of your plan is to fund improvements in this window — investing in the brand, registering IP, or hiring to reduce key-person risk — you may be able to borrow against the intangible assets you already own rather than pledging personal guarantees. See IP-backed lending: fund pre-exit improvements without a personal guarantee.
Months 6 to 0: run the process
The final window is the sale itself. With preparation done, the process is more predictable: your adviser produces a teaser and an information memorandum, approaches a curated list of buyers under NDA, and manages competing interest toward heads of terms. Diligence follows, then the sale and purchase agreement and completion.
Because deal structure drives your tax outcome, this is also where you confirm whether you are doing a share sale or an asset sale — a choice with material consequences in the UK, including for Business Asset Disposal Relief. We cover it in share sale vs asset sale.
✔ Example
An owner who spent eighteen months reducing founder dependency and documenting a proprietary process went to market with a Value Drivers Register showing thirty-one identified assets. When diligence questioned the recurring nature of the revenue, the contracts and retention data were already in the data room. The multiple held.
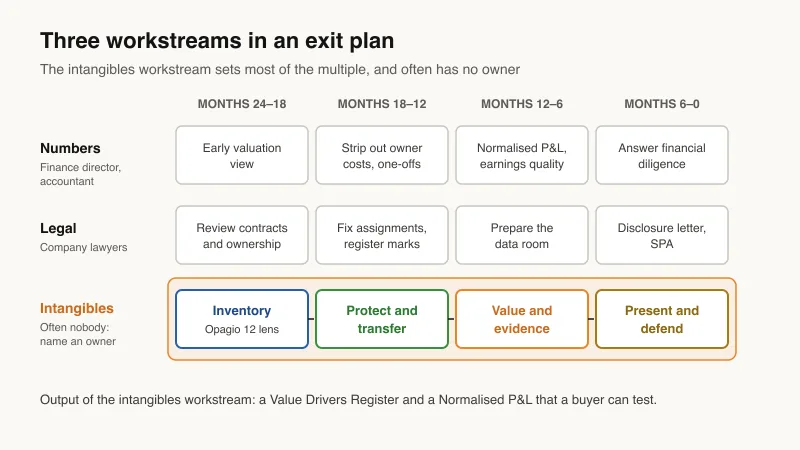
The intangibles workstream, window by window
In most exit plans the numbers have an owner, usually the finance director or the external accountant, and the legal tidy-up has an owner in the company's lawyers. The intangible assets often have nobody, even though they set most of the multiple. Treat them as a workstream of their own, with a named owner and a defined output in each window, and run it through one consistent lens: the twelve value drivers of the Opagio 12 framework, from brand and customer relationships to technology, data, processes and people. Our guide to intangible asset lifecycle management sets out who owns each stage.
The intangibles workstream in a 24-month exit plan
Window
Intangibles task
What a buyer will see
Months 24 to 18
Inventory the intangible assets across the Opagio 12 drivers; mark where value concentrates and where it is exposed
A first register of what the business owns, with the gaps marked
Months 18 to 12
Protect and transfer: register marks, confirm ownership of technology and content, move relationships and know-how from owner to business
Clear title and reduced owner dependency
Months 12 to 6
Value and evidence: value the material assets with recognised methods and tie them to normalised earnings
A Value Drivers Register and a Normalised P&L
Months 6 to 0
Present and defend: carry the register into the information memorandum and the data room, and answer diligence from it
Findings pre-empted, so the multiple holds
The intangibles workstream runs alongside the numbers and the legal tidy-up. Source: Opagio.
Opagio Intangibles supports this workstream. It identifies and classifies your intangible assets across Opagio 12, values them with recognised methods such as relief from royalty and multi-period excess earnings, and produces the Opagio Value Drivers Register and a Normalised P&L. It does not replace your corporate finance adviser, your lawyers or your tax adviser; it gives them, and the buyer, an evidence base to work from.
ℹ Note
A register is only as persuasive as its evidence. For each material asset a buyer will want to see who owns it, how it contributes to earnings and how long that contribution is likely to last. A buyer will tend to fold an asset you cannot evidence on those three points into goodwill and price it accordingly.
Two sellers, the same business, different outcomes
The clearest way to see why the twenty-four-month runway matters is to compare two owners selling the same kind of business. Both have good businesses and honest numbers. One starts preparing when a broker calls; the other starts two years out. The gap in their outcomes is not luck or negotiation — it is preparation made visible.
The unprepared seller
Goes to market on last year's statutory accounts
Revenue described as "recurring" but not evidenced
Key relationships and decisions still sit with the owner
Data room assembled reactively, under time pressure
Every diligence finding becomes a price chip or a warranty
The prepared seller
Presents a normalised profit and loss with evidenced add-backs
Retention and contract data ready before the first question
A management layer visibly runs the business
Trademarks registered; ownership of technology confirmed
Data room and disclosure prepared in advance
Findings are pre-empted, so the multiple holds
The unprepared seller is not selling a worse business. They are selling the same business with less evidence, and a buyer prices uncertainty conservatively. Each unanswered question becomes a reason to lower the offer, extend the earn-out, or demand a broader set of warranties and indemnities. The prepared seller has removed those reasons one by one over the preceding two years, so the negotiation is about price rather than about risk.
★ Key Takeaway
A buyer does not reward preparation directly. They penalise its absence. The value of starting early is measured in the price chips that never happen.
The mistakes that cost owners the most
Most disappointing exits trace back to a small number of avoidable errors, and nearly all of them are errors of timing — leaving something until the point where it can no longer be fixed without cost.
The first is starting too late, which underlies most of the others. An owner who begins three months out cannot reduce genuine founder dependency, cannot convert informal customer arrangements into contracts, and cannot register intellectual property in time to matter; they can only present what already exists. The second is confusing profit with value: focusing on squeezing another point of margin in the final year while ignoring the intangible assets and the founder-dependency question that actually set the multiple. The third is neglecting the numbers a buyer relies on — going to market without a defensible normalised EBITDA and a clean quality of earnings picture, which invites the buyer to make their own, more conservative adjustments.
The fourth is treating diligence as an event to survive rather than a test to prepare for. A buyer's advisers are paid to find reasons to pay less; an owner who has done their own vendor diligence first, and disclosed openly, controls the narrative. The fifth is leaving tax and structure to the end. Whether a sale is a share sale or an asset sale has material consequences in the UK, including for Business Asset Disposal Relief, and the most efficient structures depend on decisions — such as whether a holding company sits above the trading company — that must be in place well before completion.
⚠ Warning
The common thread is that none of these can be corrected in the final quarter. By the time a buyer is at the table, your preparation is fixed. The work that changes your price is the work you do before anyone is looking.
None of this requires you to become a corporate finance expert. It requires you to start early, to understand that most of your value is intangible, and to build the evidence for it methodically. That is the entire purpose of the twenty-four-month plan.
If you have less than two years
Not every sale allows a full runway. Health, an unsolicited approach, a partnership breakdown or simple readiness can bring a sale forward. A compressed timeline does not mean abandoning the plan; it means prioritising the parts of it that move the price most, and being honest with a buyer about the rest.
If you have twelve months, concentrate on three things. First, the numbers: produce a defensible normalised profit and loss, because a buyer will discount earnings they cannot trust, and this is the fastest high-value work you can do. Second, the evidence of what you own: identify and document your intangible assets and assemble a data room, so diligence has answers rather than gaps. Third, the most acute founder-dependency risks: you may not have time to build a full management layer, but you can document the critical processes and start distributing your most important customer relationships.
If you have six months, be realistic. You are unlikely to change the fundamental shape of the business, so the priority shifts to presentation and disclosure — evidencing what is genuinely there, and disclosing openly what is not, so that surprises do not derail the process late. A buyer will forgive a known weakness that is disclosed early; they will re-price a weakness they discover for themselves in diligence.
ℹ Note
A shorter runway raises the value of preparation you can still do, because the alternative is letting the buyer's advisers frame every gap. Even a few weeks spent building a normalised profit and loss and a data room changes the tone of the negotiation.
The judgement in a compressed sale is knowing which gaps to close and which to disclose. Closing a gap takes time you may not have; disclosing it costs nothing and protects the relationship. The owners who sell well on a short timeline are the ones who are candid about where the business is, and who put the evidence for its real strengths — most of them intangible — in front of the buyer before the buyer goes looking.
The plan on one page
Selling a business well is not a single event; it is a two-year programme that moves value out of your head and onto the record. Understand what you own, fix the leaks, build the evidence, then run the process. Owners who do this in that order consistently outperform those who compress it into the final quarter, because the compressed version leaves too much of the business's value undocumented and therefore unpriced.
The through-line of the whole plan is that most of what a buyer pays for is intangible — your brand, your customers, your technology, your processes and your people — and almost none of it appears on the balance sheet a buyer is handed. The two-year runway exists to make that hidden value visible and defensible before anyone is negotiating over it. That is the difference between accepting the number you are offered and defending the number the evidence supports.
Exit planning is the preparation of a business and its owner for a sale or other exit, usually over one to three years before going to market. It covers the route and timing, reducing owner dependency, protecting and evidencing the intangible assets, normalising the numbers and, with advice, the structure of the sale.
When should I start exit planning?
About twenty-four months before you intend to go to market. The issues that lower a sale price, such as owner dependency, customer concentration, informal contracts and unregistered intellectual property, take a year or more to fix. With twelve months or less, prioritise the numbers, the evidence of what you own and the most acute dependency risks.
What is the difference between an exit plan and an exit strategy?
An exit strategy is the intended route out: a trade sale, a management buyout, a sale to private equity or an employee ownership trust. An exit plan is the programme of work that prepares the business for that route and protects the price. Most owners need both, and the plan should be built around the strategy they choose.
What is owner dependency and why does it lower the price?
Owner dependency is the extent to which earnings rely on the owner's personal decisions, knowledge and relationships. A buyer pays for earnings they will receive after the owner leaves, so dependency is priced as risk: a lower multiple, a larger earn-out, or a tie-in that keeps the owner working after completion.
Does exit planning include tax planning?
It should include taking advice early, because the structure of a sale affects the tax outcome. In the UK, whether the sale is of shares or assets, and how the business is owned, can affect reliefs such as Business Asset Disposal Relief. The rates, limits and conditions are set in UK tax law, published by HMRC, and they change, so confirm the position with a UK tax adviser. This guide is general information, not tax advice.
Ivan Gowan is Founder and CEO of Opagio. He spent twenty-five years in fintech, including at IG Group, before building Opagio to help owners see and evidence the intangible value in their businesses. Meet the team.
A buyer's diligence is designed to find the weaknesses you left too late to fix. This is the owner's checklist for getting a business ready to sell — and ready to survive that scrutiny.
A seller wants a share sale. A buyer usually wants an asset sale. The structure you land on decides your tax, your risk and how the intangibles are valued. Here is the UK trade-off.
A business that cannot run without its founder is a business a buyer will not pay full price for. Here is the programme to fix that in the 12–24 months before you sell.
Eight ways to exit a UK owner-managed business, compared on price, speed, certainty, control and tax: trade sale, private equity, MBO, MBI, employee ownership trust, IPO, family succession and an orderly wind-down.
Get the latest insights on intangible asset growth and productivity delivered to your inbox.
We use essential cookies to make our website work. We'd also like to use analytics cookies to improve your experience. You can manage your preferences at any time.
Cookie Policy