Our Data Processing Agreement changes on 2 November 2026.
Version 3.0 changes what it says about how our AI service providers handle the data we send them. There is no new sub-processor.
Read what is changing
Our Privacy Policy changes on 9 November 2026.
Version 5.1 updates how we use information about your use of Opagio and our emails, how we handle enquiries, and the service providers that help us.
Read what is changing
How to Calculate Goodwill: Formula, Partial vs Full Goodwill Example
By Tony Hillier· 2026-05-18goodwillifrs-3ppam-and-aintangible-assetsconsolidated-goodwillpartial-goodwillfull-goodwillnon-controlling-interestfrs-102
To calculate goodwill, add the consideration transferred, the non-controlling interest (NCI) and the fair value of any interest the buyer already held, then subtract the fair value of the identifiable net assets acquired; what is left is goodwill. On a 100% acquisition that is simply the price paid less the fair value of the net assets. When less than 100% is bought, the way the NCI is measured decides the answer: at its share of the net assets (the partial goodwill method) or at its fair value (the full goodwill method).
Last reviewed: October 2026. Covers IFRS 3, ASC 805 and FRS 102 as amended by the FRC's Periodic Review 2024, which applies to accounting periods beginning on or after 1 January 2026.
£17.0mgoodwill on the worked example's £25.0m acquisition of 100%
£13.6m vs £16.6mpartial vs full goodwill when the same target is bought 80% for £20.0m
10 yearsmaximum goodwill life under FRS 102 where it cannot be reliably estimated
ℹ Note
Goodwill is a residual. The smaller the goodwill line, the more rigorous the purchase price allocation behind it; a bloated goodwill line usually means identifiable intangibles have been missed.
The goodwill formula
The goodwill formula is set out in IFRS 3 paragraph 32. The acquirer measures goodwill as the excess of (a) the aggregate of the consideration transferred, the amount of any non-controlling interest in the acquiree, and the acquisition-date fair value of any previously held equity interest, over (b) the net of the acquisition-date amounts of the identifiable assets acquired and the liabilities assumed, measured in accordance with the standard.
Goodwill formula components (IFRS 3)
Goodwill formula component
Source
Consideration transferred
Fair value of cash, shares, and contingent consideration paid
Non-controlling interest
Either fair value or proportionate share of identifiable net assets (IFRS 3 paragraph 19)
Previously held interest
Fair value of any pre-existing equity stake in the acquiree
Less: Net identifiable assets
Identifiable assets less liabilities assumed, all at fair value
= Goodwill
The residual
In equation form: Goodwill = Consideration Transferred + Non-Controlling Interest + Fair Value of Previously Held Interest − Net Fair Value of Identifiable Assets and Liabilities. Every one of those terms is measured at the acquisition date. If the result is negative, you do not have goodwill. You have a bargain purchase, which IFRS 3 recognises in profit or loss once the inputs have been reassessed (paragraphs 34 to 36). FRS 102 treats negative goodwill differently: it is shown below goodwill on the balance sheet and released to profit or loss as the non-monetary assets are recovered (paragraph 19.24).
★ Key Takeaway
Goodwill is a residual, not a valuation. You do not calculate goodwill by valuing goodwill. You calculate every other line, and goodwill is what is left.
Worked example: a £25m UK acquisition
Acquirer Ltd buys 100% of the shares of Target Ltd on 31 May 2026 for £25.0m cash. There is no previously held equity interest and no non-controlling interest. The group reports under IFRS. Below is the line-by-line working.
Step 1: Consideration transferred
Consideration transferred is measured at acquisition-date fair value under IFRS 3 paragraph 37. For a cash deal, that is the cash paid. For share consideration, it is the market value of the shares issued on the acquisition date. For deferred or contingent consideration, it is the fair value of the future payment stream.
Consideration transferred (£m)
Component
£m
Cash on completion
25.0
Shares issued
—
Contingent consideration
—
Consideration transferred
25.0
Step 2: Identify and measure identifiable assets
Identifiable assets include both tangible and intangible items. The discipline is to identify every intangible that meets the IFRS 3 separability or contractual-legal criteria, and to measure each at fair value.
Identifiable assets at fair value (£m)
Identifiable asset class
£m
Property, plant and equipment
2.5
Net working capital (receivables, inventory, payables)
1.8
Cash and equivalents
0.7
Customer relationships (5-year average life)
3.2
Technology and software
1.6
Trade names
0.9
Order backlog
0.3
Total identifiable assets at fair value
11.0
The four intangible lines (customer relationships, technology, trade names and order backlog, £6.0m in total) are what separates a rigorous calculation from a lazy one. Acquirers who skip the intangible identification step push the entire economic value of the target into goodwill, fall short of the IFRS 3 recognition requirement, and leave annual impairment testing to carry a number that should have been amortised against earnings.
Step 3: Identify and measure liabilities assumed
Liabilities assumed at fair value (£m)
Liability class
£m
Trade and other payables
0.6
Bank borrowings
0.9
Deferred tax liability on the intangible step-ups
1.5
Total liabilities assumed at fair value
3.0
The deferred tax line is the one most frequently mis-stated. In a UK share purchase the target's tax bases do not change, so the £6.0m of newly recognised intangibles has a tax base of nil. That temporary difference must be recognised as a deferred tax liability under IAS 12 paragraph 19: £6.0m × 25% (the UK main rate of corporation tax) = £1.5m. The example assumes the tangible assets and working capital are carried at fair values equal to their tax bases, so no other deferred tax arises.
Step 4: Calculate net identifiable assets
Net identifiable assets = Total identifiable assets − Total liabilities assumed
= £11.0m − £3.0m = £8.0m.
Of the £25.0m paid, £8.0m is identifiable net assets (which include the £6.0m of separately identified intangibles, net of the £1.5m deferred tax liability on them) and £17.0m is goodwill. The intangibles will amortise through profit or loss over their useful lives; under IFRS the goodwill will not amortise but will be tested for impairment every year.
The consolidated goodwill formula
The consolidated goodwill formula is the same IFRS 3 formula, applied in the group accounts of a parent that controls but does not wholly own the target:
Consolidated goodwill = Consideration transferred + Non-controlling interest + Fair value of any previously held interest − Fair value of identifiable net assets (100%)
The identifiable net assets are always taken at 100%, because the group consolidates all of the subsidiary's assets and liabilities, not just its own share. The NCI line is where the choice sits, and there are only two ways to fill it:
Partial (proportionate) goodwill
NCI = NCI % × fair value of identifiable net assets Goodwill = Consideration + NCI's share of net assets − Net assets Equivalent to: Consideration − Parent % × Net assets
Full (fair value) goodwill
NCI = fair value of the NCI at the acquisition date Goodwill = Consideration + NCI at fair value − Net assets Includes the goodwill attributable to the NCI
📚 Definition
The goodwill attributable to the NCI is the difference between the two methods: NCI at fair value minus NCI at its proportionate share of identifiable net assets. The partial method never recognises it; the full method does.
Where the buyer already held a stake before gaining control (a step acquisition), that stake is remeasured to fair value at the acquisition date, any gain or loss goes to profit or loss, or to other comprehensive income where the stake was an equity investment held at fair value through OCI (IFRS 3 paragraph 42), and the remeasured amount enters the formula alongside the consideration.
Partial vs full goodwill: a worked example with NCI
Take the same Target Ltd and the same acquisition date, but this time Acquirer Ltd buys 80% of the shares for £20.0m cash. Everything else is unchanged.
Inputs to the 80% example (£m)
Input
£m
Basis
Consideration transferred
20.0
Cash for 80% of the shares
Fair value of identifiable net assets
8.0
Step 4 above, at 100%
Fair value of the 20% NCI
4.6
20% × £25.0m = £5.0m, less an 8% discount for lack of control
The price implies an equity value of £25.0m (£20.0m ÷ 80%), the same as the 100% deal. Twenty per cent of that is £5.0m, but a minority holder cannot direct the business, so its shares are worth less per share than the controlling stake. An 8% discount for lack of control gives £5.0m × 92% = £4.6m. IFRS 3 paragraph B45 recognises that the per-share fair values of the controlling and non-controlling interests can differ for exactly this reason.
Goodwill calculation with NCI, both methods (£m)
Line
Partial goodwill method
Full goodwill method
Consideration transferred
20.0
20.0
Add: non-controlling interest
1.6 (20% × 8.0)
4.6 (fair value)
Subtotal
21.6
24.6
Less: fair value of identifiable net assets
(8.0)
(8.0)
Goodwill recognised
13.6
16.6
of which attributable to the parent
13.6
13.6
of which attributable to the NCI
—
3.0
✔ Example
Partial goodwill method: £20.0m + (20% × £8.0m = £1.6m) − £8.0m = £13.6m. Full goodwill method: £20.0m + £4.6m − £8.0m = £16.6m. The £3.0m difference is the goodwill attributable to the NCI: £4.6m at fair value less £1.6m at its share of net assets.
The parent's goodwill is the same under both methods: £20.0m − (80% × £8.0m = £6.4m) = £13.6m. The method only decides whether the NCI's share of goodwill reaches the balance sheet. Both consolidations balance: what the group recognises (net identifiable assets plus goodwill) equals the consideration plus the NCI in equity. Partial: £8.0m + £13.6m = £21.6m = £20.0m + £1.6m. Full: £8.0m + £16.6m = £24.6m = £20.0m + £4.6m.
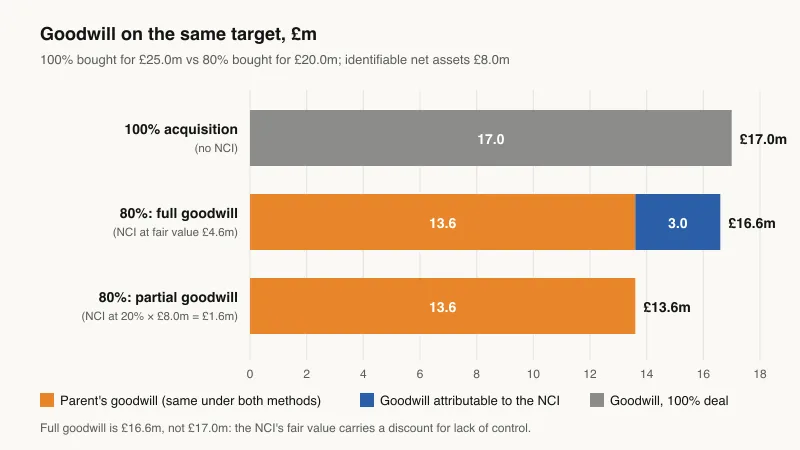
Partial vs full goodwill on the worked example (£m): the parent's £13.6m does not move; the method decides whether the NCI's £3.0m is recognised.
Note what full goodwill is not. It is not the partial figure grossed up pro rata (£13.6m ÷ 80% = £17.0m, the 100% answer). Because the NCI's fair value carries a discount for lack of control, full goodwill here is £16.6m, £0.4m below the 100% figure. If the NCI were valued at a straight 20% of the £25.0m equity value, the two would coincide.
★ Key Takeaway
The partial vs full choice changes goodwill, NCI in equity and total assets by the same amount, the goodwill attributable to the NCI. It never changes the parent's goodwill or the consideration paid.
Which method applies: IFRS 3, US GAAP and FRS 102
★ Key Takeaway
The three frameworks a UK group is most likely to meet answer the NCI question differently. IFRS 3 offers a choice, US GAAP requires fair value, and FRS 102 allows only the proportionate share.
IFRS 3 (paragraph 19): for each business combination, the acquirer chooses to measure the NCI at fair value or at its proportionate share of the recognised amounts of the identifiable net assets. The choice is made transaction by transaction, not as a group-wide policy. It applies only to present ownership interests that entitle their holders to a proportionate share of net assets on liquidation; other components of NCI (for example, preference shares without that entitlement) are measured at fair value, unless another IFRS requires a different basis (IFRS 2 for the acquiree's share-based payment awards, for example).
US GAAP (ASC 805-20-30-1): the acquirer measures the NCI at fair value at the acquisition date. The partial method is not available, so US GAAP always produces full goodwill.
FRS 102 (paragraphs 19.14A and 19.22): the NCI is stated at its share of the net amount of the identifiable assets, liabilities and provisions for contingent liabilities, and goodwill is the cost of the combination less the acquirer's interest in that net amount. There is no fair value option, so FRS 102 goodwill is always partial goodwill.
NCI and goodwill by framework
Topic
IFRS 3
ASC 805 (US GAAP)
FRS 102 Section 19 (UK and Ireland)
Non-controlling interest
Fair value or proportionate share of net assets, chosen per transaction
Fair value
Proportionate share of net assets
Goodwill recognised
Partial or full
Full
Partial (acquirer's interest only)
The 80% worked example
£13.6m or £16.6m
£16.6m
£13.6m plus directly attributable costs, if the net assets were the same
Transaction costs
Expensed
Expensed
Included in the cost of the combination
Goodwill after acquisition
Not amortised; annual impairment test (IAS 36)
Not amortised; impairment test (ASC 350); private companies may elect amortisation over up to 10 years (ASU 2014-02)
Amortised over its useful life; no more than 10 years if the life cannot be reliably estimated (19.23)
⚠ Warning
The FRS 102 figure is only comparable if the net assets are. FRS 102 recognises an intangible acquired in a business combination separately only if it is both separable and arises from contractual or legal rights (unless the group chooses the wider policy), so fewer intangibles typically reach the balance sheet and more value sits in goodwill. The PPA guide sets out the recognition differences in full.
For a group that reports to a US parent, the practical choice is narrower than IFRS 3 suggests: the US GAAP numbers need full goodwill whatever the UK statutory accounts elect. The IFRS 3 vs ASC 805 comparison sets out the other differences between the two standards.
Why goodwill is a residual, not a valuation
Goodwill is not an asset you can point to. It is what the acquirer paid for the synergies it expects from the combination (the term IAS 36 paragraph 80 uses when goodwill is allocated to cash-generating units), the assembled workforce (which is not separately recognisable under IFRS 3 paragraph B37), market positioning, expected future growth, and the simple fact that the target was worth more as a going concern than the sum of its separately measurable parts.
That residual character matters because it changes how the figure is governed. A valuation of customer relationships using multi-period excess earnings is defended on cash flow, attrition and contributory asset charges. A goodwill figure is defended only by the rigour of every line above it. There is no goodwill model to challenge, only the assumption that nothing was missed.
The smaller the goodwill, the stronger the underlying allocation. Auditors, PE valuation committees and tax authorities all read a high goodwill line as a signal that the purchase price allocation was thin. Founders selling to a strategic buyer should expect the buyer's auditor to push hard on intangible identification precisely to keep goodwill low.
Identifying separable intangibles before you arrive at goodwill
Before the goodwill figure can be computed, every separately identifiable intangible asset must be recognised at fair value. Under IFRS 3, an intangible is identifiable if it is either separable (capable of being sold, licensed, transferred or exchanged, individually or together with a related contract) or contractual-legal (arising from contractual or legal rights, regardless of whether those rights are transferable).
The five most commonly recognised intangible classes in a typical mid-market acquisition are set out below.
Common intangible classes in a mid-market PPA (IFRS 3)
Intangible class
Recognition basis
Typical valuation method
Customer relationships
Separable
Multi-period excess earnings (MPEEM)
Technology and software
Separable + contractual-legal
Relief from royalty (RFR)
Trade names and trademarks
Contractual-legal
Relief from royalty (RFR)
Order backlog
Contractual-legal
Margin in backlog
Non-compete agreements
Contractual-legal
With-and-without (W&W)
If the acquirer fails to recognise these, the missed value piles into goodwill, distorting the balance sheet, deferring the amortisation that should have hit earnings, and creating a future impairment risk that the audit committee will eventually have to answer for.
ℹ Note
Assembled workforce is explicitly excluded from separate recognition under IFRS 3 paragraph B37. The cost of replacing a workforce is part of goodwill, even where it is materially valuable. Under FRS 102 the test is stricter: an acquired intangible is recognised separately only if it is both separable and contractual-legal, unless the group adopts the wider policy.
IFRS 3 measurement period rules
IFRS 3 paragraph 45 grants a measurement period during which the acquirer can adjust the provisional amounts recognised at the acquisition date. The measurement period cannot exceed twelve months from the acquisition date and ends as soon as the acquirer receives the information needed to finalise the accounting (paragraph 45).
★ Key Takeaway
Three rules govern the measurement period: retrospective adjustment, acquisition-date conditions only, and a twelve-month hard stop.
Rule 1: Retrospective adjustment. Provisional amounts are adjusted retrospectively, as if the accounting for the business combination had been completed at the acquisition date (paragraph 49). The comparative information for prior periods is restated, including any change in depreciation, amortisation or other income effects.
Rule 2: New information about acquisition-date conditions. Only information about facts and circumstances that existed at the acquisition date can be reflected through measurement-period adjustments (paragraph 47). Post-acquisition events are accounted for in profit or loss, not retrospectively.
Rule 3: Twelve-month hard stop. After the measurement period ends, the accounting for the business combination is revised only to correct an error under IAS 8 (paragraph 50). Later changes that are not errors, such as remeasuring liability-classified contingent consideration, go through profit or loss and leave goodwill untouched.
Measurement period at a glance
Measurement period item
IFRS 3 reference
Practical effect
Maximum duration
Paragraph 45
Twelve months from acquisition date
Retrospective adjustment
Paragraph 49
Prior-period comparatives restated
Acquisition-date conditions only
Paragraph 47
Post-acquisition events go to P&L
After the period ends
Paragraph 50 and IAS 8
Goodwill changes only to correct an error
In practice, the measurement period is the window in which the PPA gets finalised. A provisional goodwill figure recognised on completion is replaced by the final figure once the PPA work has been completed by the independent valuer.
Annual impairment testing: no amortisation under IFRS
IFRS does not permit goodwill to be amortised. Instead, IAS 36 paragraph 10 requires that goodwill be tested for impairment at least annually, and more frequently if there are indicators of impairment. The test is performed at the level of the cash-generating unit (CGU) to which goodwill has been allocated.
The annual test compares the recoverable amount of the CGU (the higher of fair value less costs of disposal and value in use) with its carrying amount. If carrying amount exceeds recoverable amount, an impairment loss is recognised: first against goodwill, then pro rata against the other assets of the CGU (paragraph 104). Goodwill impairment testing is where the partial vs full choice comes back.
Impairment with an NCI: the IAS 36 gross-up
Under the partial method, the goodwill attributable to the NCI is not on the balance sheet, but the cash flows that support it are still in the CGU's recoverable amount. Comparing a recoverable amount for 100% of the business with a carrying amount that holds only the parent's goodwill would make the unit look healthier than it is. IAS 36 Appendix C therefore requires the carrying amount of goodwill to be notionally grossed up to include the NCI's share before the comparison (paragraph C4). Any loss is then allocated between the parent and the NCI on the same basis as profit or loss (paragraph C6), and only the part relating to recognised goodwill is booked (paragraph C8). FRS 102 contains the same notional gross-up (paragraph 27.26). Under US GAAP the NCI's goodwill is already recognised, so no gross-up arises.
Continue the 80% example to the first year-end. Target Ltd is a single CGU, its net identifiable assets are still carried at £8.0m (held flat for illustration), and the recoverable amount has fallen to £22.0m.
Year-one impairment test with an NCI (£m)
Line
Partial goodwill method
Full goodwill method
Goodwill recognised
13.6
16.6
Notional gross-up for the NCI (13.6 ÷ 80% − 13.6)
3.4
—
Goodwill for the test
17.0
16.6
Net identifiable assets
8.0
8.0
Carrying amount tested
25.0
24.6
Recoverable amount
22.0
22.0
Impairment loss on the CGU
3.0
2.6
Impairment recognised
2.4 (parent's 80%; the NCI's 0.6 relates to unrecognised goodwill)
2.6 (2.08 to the parent, 0.52 to the NCI)
Goodwill after the test
11.2
14.0
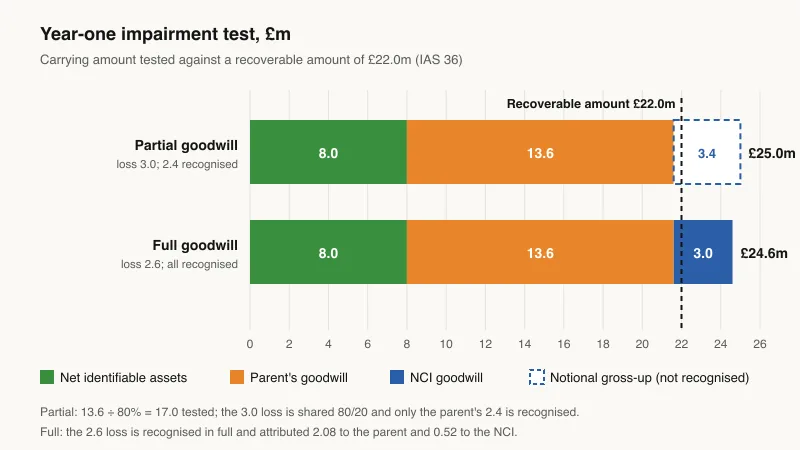
The IAS 36 gross-up on the worked example (£m): same business, same recoverable amount, a £2.4m charge under partial goodwill and £2.6m under full goodwill.
The gross-up is a pro rata figure (£3.4m), not the NCI's actual fair-value goodwill (£3.0m). That is why the two methods can produce different losses on the same business, and why partial goodwill does not escape impairment: it is tested as if the whole of the goodwill were recognised.
⚠ Warning
Under US GAAP ASC 350, private companies and not-for-profit entities can elect to amortise goodwill over up to ten years and apply a simplified impairment model. Public companies under ASC 350 do not amortise and test at least annually, at reporting-unit level. If your group reports under both IFRS and US GAAP, the goodwill line will sit at different values in the two sets of accounts.
Under FRS 102 in the UK, goodwill arising on a business combination is amortised over its useful life (paragraph 19.23(a)), which must not exceed ten years where the useful life cannot be reliably estimated. On £13.6m of goodwill from the 80% example, a 10-year life would mean a charge of £1.36m a year. A group moving from FRS 102 to IFRS that uses the IFRS 1 business-combinations exemption carries goodwill forward at its FRS 102 carrying amount at the transition date, after a mandatory impairment test, and does not reverse the amortisation already charged (IFRS 1 Appendix C, paragraph C4(g) and (h)).
Common mistakes founders and CFOs make
Six mistakes recur on almost every acquisition we see.
⚠ Warning
Each of these is a recurring audit-committee discussion item, and each is avoidable with a properly scoped purchase price allocation.
Mistake 1: Stuffing the intangibles line into goodwill. Customer relationships, technology and trade names get rolled into goodwill because the acquirer either does not commission a PPA or commissions one with no time pressure. The audit committee inherits an impairment risk that should never have been there.
Mistake 2: Forgetting the deferred tax liability on fair-value uplifts. The DTL is part of liabilities assumed and reduces net identifiable assets. Acquirers who ignore it understate goodwill at completion and then have to increase it when the auditor picks up the omission, a particularly painful set of journals to post.
Mistake 3: Treating contingent consideration as zero. Contingent consideration is measured at acquisition-date fair value, even where the trigger conditions are uncertain. Afterwards, equity-classified contingent consideration is not remeasured and its settlement is accounted for within equity; liability-classified contingent consideration is remeasured at fair value at each reporting date, with changes in profit or loss (IFRS 3 paragraph 58).
ℹ Note
The most common audit adjustment we see on mid-market goodwill calculations is the deferred tax liability on intangible step-ups. If the intangible work is done properly but the DTL is missed in a UK share purchase, goodwill is understated by 25% of the step-up at the UK main rate of corporation tax: £1.5m in the £25m worked example.
Mistake 4: Using the non-controlling interest line as a plug. Under IFRS 3 paragraph 19, NCI is measured either at fair value (the full goodwill method) or at its proportionate share of identifiable net assets (the partial goodwill method). The choice is made transaction by transaction and disclosed, and the fair value needs its own evidence, including any discount for lack of control.
Mistake 5: Applying the wrong framework's NCI rule. A UK subsidiary group reporting under FRS 102 cannot use full goodwill, and a US GAAP parent cannot use partial goodwill. Where the same acquisition is consolidated under two frameworks, keep a reconciliation of the NCI and goodwill lines from day one.
Mistake 6: Stopping at the formula. The formula gives you a number. The defence of that number lives in the workpapers: the valuation reports for each identifiable intangible, the deferred-tax computation, the contingent-consideration valuation, the NCI fair value, the measurement-period correspondence. Without the workpapers, the figure is indefensible at any subsequent audit or due diligence cycle.
Frequently Asked Questions
What is the formula for calculating goodwill?
Goodwill = consideration transferred + non-controlling interest + fair value of any previously held interest − fair value of the identifiable net assets acquired (IFRS 3 paragraph 32). On a 100% acquisition with no earlier stake, it is the price paid less the fair value of the net assets: £25.0m − £8.0m = £17.0m in the worked example.
What is the difference between partial and full goodwill?
Under the partial goodwill method the NCI is measured at its share of the identifiable net assets, so only the parent's goodwill is recognised. Under the full goodwill method the NCI is measured at fair value, so goodwill also includes the NCI's share. In the 80% example, partial goodwill is £13.6m and full goodwill is £16.6m; the £3.0m difference is the goodwill attributable to the NCI.
How do you calculate goodwill with a non-controlling interest?
Add the consideration and the NCI, then subtract 100% of the fair value of the identifiable net assets. The NCI is either its percentage of those net assets (partial) or its fair value (full). For 80% bought for £20.0m with net assets of £8.0m: partial is £20.0m + £1.6m − £8.0m = £13.6m; full, with an NCI fair value of £4.6m, is £20.0m + £4.6m − £8.0m = £16.6m.
Can UK companies use the full goodwill method?
It depends on the framework. A UK group reporting under UK-adopted IFRS can choose either method for each acquisition (IFRS 3 paragraph 19). A UK group reporting under FRS 102 cannot: paragraph 19.14A states the NCI at its share of the net amount of identifiable assets, liabilities and provisions for contingent liabilities, so FRS 102 goodwill is always partial.
Why is partial goodwill grossed up for impairment testing?
Because the CGU's recoverable amount covers the whole business, including the cash flows behind the NCI's unrecognised goodwill. IAS 36 paragraph C4 (and FRS 102 paragraph 27.26) notionally grosses up the goodwill to include the NCI's share before the comparison, so the test compares like with like. Only the parent's share of any goodwill loss is then recognised.
Where to go next
If you are sitting in front of a deal, the next steps are operational, not theoretical.
✔ Example
A buyer that runs intangible identification at heads of terms has the intangible valuations, the deferred tax and the NCI fair value ready before completion, so the provisional goodwill figure needs fewer measurement-period adjustments and is easier to defend at the first impairment test.
Open the purchase price allocation workstream the day heads of terms are signed, not the day after completion. The earlier the identifiable intangible work starts, the smaller and more defensible the goodwill line.
Run the numbers on your own balance sheet. See how Opagio Intangibles identifies and values the intangible assets that need to come out of goodwill before the formula is applied, and how Opagio works with scale-up companies preparing for acquisitions, diligence and exit.
Tony Hillier is Chairman of Opagio. Thirty years in structured finance and corporate transactions, ex-NM Rothschild and GEC Finance. Opagio builds the intangible asset evidence platform that institutional investors expect.About the team →
Share:
TH
Tony Hillier — Chairman, Co-Founder
MA, Balliol College, University of Oxford | Harvard Business School MBA with Distinction
IFRS 3 and ASC 805 both require the acquisition method for business combinations, but the two frameworks diverge on goodwill measurement, the measurement period, contingent consideration, restructuring provisions, and several other practical mechanics. A CFO who treats the two as interchangeable lands a different goodwill number, a different intangible split, and a different EPS profile. This guide walks through the divergence points paragraph by paragraph.
The brand valuation formula every founder, CFO and PE partner should know — Relief from Royalty walked through input by input, with a worked example for a £40m UK consumer brand and a side-by-side comparison against Interbrand and Brand Finance.
Since 5 August 2026, UK-incorporated AIM companies may report under FRS 102 instead of IFRS. What the change means for goodwill, development costs and acquired intangibles, and how to choose a framework before a float.
Patent valuation in practice: what drives how much a patent is worth, the four methods valuers use under IVS 210, and a relief-from-royalty calculation that reconciles line by line over a UK patent's remaining legal life, with no terminal value after expiry.
We use essential cookies to make our website work. We'd also like to use analytics cookies to improve your experience. You can manage your preferences at any time.
Cookie Policy