Earn-Outs in a Business Sale: Structure, Clauses and Warranties
By Ivan Gowan· 2026-07-06earn out business saleearn outearn out structureearn out clausewarranties and indemnitiesdisclosure letterdeferred considerationselling a businessexit
An earn-out is the part of a business sale price that the buyer pays after completion, and only if the business meets agreed targets over a set period, usually one to three years. The buyer pays a fixed sum when the deal completes and a further, conditional sum later, measured against revenue, gross profit, EBITDA or a specific milestone. In an earn out business sale, the earn-out clause therefore decides how much of the headline price the seller actually receives.
Last reviewed: October 2026. Written for owners of UK businesses; tax points are general information on UK rules, not tax advice.
Most owners treat the day heads of terms are signed as the finish line. The number is agreed, hands are shaken, and the sale feels done. It is not. The headline price is a statement of intent, not a payment. What you actually walk away with is decided in the weeks and months that follow: in how the earn-out is structured, what you warrant to be true about the business, what the disclosure letter protects, and how much of the money is held back until conditions are met. An owner who understands the headline number but not this second half of the deal can sign a strong price and receive a weak one.
ℹ Note
This guide is written from the seller's side of the table, for owners of UK businesses turning over roughly £1m to £100m. It covers the earn-out structure and the clause terms worth negotiating, with a worked example; how intangible assets drive earn-out risk; the UK tax points to raise with your adviser; and the warranties, disclosure letter, escrow and deferred consideration that follow completion. It is general information, not legal or tax advice.
The headline price and the money you keep are two different numbers
The first thing to internalise is that the price on the heads of terms and the cash that reaches your account are rarely the same figure. Between them sit a set of mechanisms (deferred payments, performance conditions, holdbacks and potential clawbacks) that a buyer uses to shift risk from themselves onto you. Every one of them is negotiable. None of them is automatic.
A buyer's logic is straightforward. They are paying for a stream of earnings they believe will continue, and for assets they believe will transfer. Until they can see that both have survived the change of ownership, they would rather not part with all the cash. So they defer part of it, tie part of it to future performance, and hold part of it back against the risk that something you told them turns out to be untrue. Understanding each of these before you sign is the difference between negotiating the structure and simply accepting it.
★ Key Takeaway
The headline price is a ceiling, not a promise. Deferred consideration, an earn-out and a warranty claim can each pull the number you actually receive well below it. Negotiate the structure with the same seriousness you brought to the price, because the structure is where the price is quietly decided.
The mechanics of all this are settled in the sale and purchase agreement, the long-form contract that supersedes the heads of terms and governs everything that follows. By the time you are negotiating the agreement, the price is largely fixed. What remains in play is how, and how certainly, you get paid.
It helps to keep value and consideration apart. A valuation answers what the business is worth; our guide on how to value a business sets out the methods a buyer uses to reach a price. The consideration structure answers a different question: how much of that price is paid at completion, how much later, and on what conditions. Two offers at the same headline price can be worth very different amounts once the structure is priced in.
Earn-out structure: the terms that decide the payout
An earn-out ties part of the sale price to the business hitting agreed targets after completion. Instead of paying the full amount up front, the buyer pays a base figure at completion and a further, conditional amount if the business performs to plan over a defined period. In accounting terms it is a form of contingent consideration: payable only if specified future conditions are met.
Earn-outs exist because they bridge a gap in belief. You think the business is worth more than the buyer will pay in cash today; the buyer is willing to pay it, but only if the performance you promise actually materialises. The earn-out lets both sides bank the disagreement: you get the chance to earn the higher number, and the buyer only pays it if the results arrive. Every earn-out structure is built from the same handful of terms.
Earn-out structure terms at a glance
Term
What it sets
What a seller should look for
Metric
What performance is measured: revenue, gross profit, EBITDA, a milestone or customer retention
A metric you can influence and the buyer cannot easily move
Period
How long performance is measured, usually one to three years, year by year or cumulatively
Cumulative measurement or a catch-up, so one weak year is not final
Threshold
The level of performance below which nothing is paid
A threshold set from the business plan the price was based on, not a stretch case
Payment curve
How payment rises between threshold and target: straight-line, stepped, or all-or-nothing (a "cliff")
A sliding scale rather than a cliff
Cap
The maximum earn-out payable
A cap that reflects the upside you gave up in the cash price
Floor
A minimum earn-out payable whatever the result
Rarely conceded, but worth asking for where the buyer controls the outcome
Acceleration
Events that make the earn-out payable early, usually in full
Sale of the business, integration, breach of covenant
Buyer covenants
How the buyer must run the business during the period
Ring-fencing, conduct-of-business protections and information rights
The metric: revenue, gross profit or EBITDA
The metric an earn-out is measured against matters more than almost anything else in the deal, because it determines how much control you keep over your own outcome.
Common earn-out metrics compared
Structure
Measured against
Seller's exposure
Revenue-based
Top-line turnover over the earn-out period
Lower risk of manipulation, but rewards volume the buyer may not want
Gross profit-based
Revenue less direct costs over the period
Shields you from central overhead, but exposed to the buyer's pricing and cost-of-sales decisions
Profit / EBITDA-based
Normalised earnings over the period
Highest risk: the buyer controls the costs that determine profit
Milestone-based
Specific events (a contract renewal, a product launch, a headcount target)
Cleaner to measure, but binary: you hit it or you do not
Retention-based
Named customers or key staff staying on
Depends on relationships you may no longer control post-sale
Revenue-based earn-outs are the hardest for a buyer to game, because turnover is difficult to suppress without damaging the business they now own. Profit-based earn-outs are the most dangerous for a seller, because the buyer controls the cost base, and every pound of new central overhead, management charge or reallocated cost they push into your business reduces the profit your earn-out is measured against. Gross profit sits between the two and is often a workable compromise where the buyer insists on a margin-sensitive measure.
1–3 yrstypical earn-out period after completion
10–50%of total consideration commonly placed at risk
EBITDAthe metric a seller should be most wary of
The figures above are ranges, not rules; every deal is negotiated on its own facts. But they frame the exposure. If half your consideration is riding on an EBITDA target for three years, and you no longer control the cost base that determines EBITDA, you have accepted a great deal of risk for a number you cannot fully influence.
Period, threshold, cap and floor
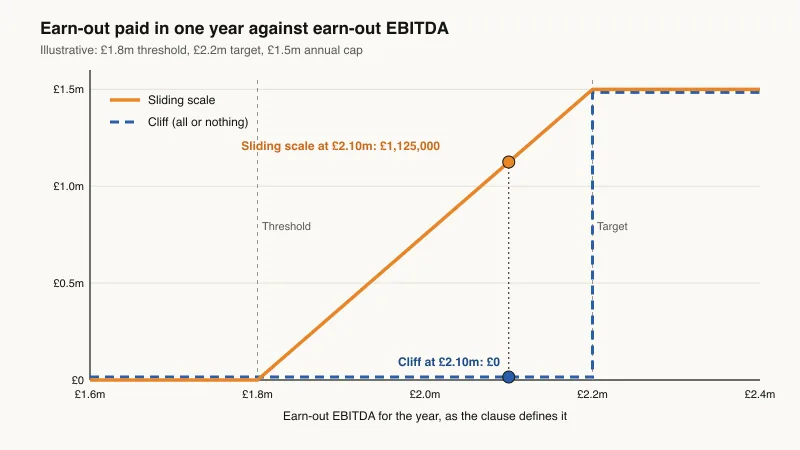
Year-by-year measurement gets cash to you sooner, but a single weak year can be lost for good; cumulative measurement, or a catch-up that lets a strong later year recover a shortfall, means a contract that slips from December into January does not cost you a year's earn-out. Below the threshold nothing is paid and at the target the cap is paid. In between, a sliding scale pays in proportion, while a cliff pays nothing until the target is met in full. A floor is uncommon, but it is a fair request where the buyer will control most of what determines the result.
Illustration: one year of the worked example below. A sliding scale pays £1,125,000 at £2.10m of EBITDA; a cliff pays nothing until £2.2m.
Acceleration on change of control
An earn-out assumes the business you sold still exists in a measurable form for the whole period. If the buyer sells it on, merges it into another division or is itself acquired, the metric can become impossible to measure. An acceleration clause deals with this by making the earn-out payable early, usually at the maximum or at a pre-agreed amount, if specified events occur. The usual triggers are a sale of the business or of the buyer's group (a change of control), integration that ends separate measurement, a material breach of the buyer's covenants, and the buyer's insolvency.
Buyer covenants: ring-fencing and conduct of business
Covenants are the buyer's written promises about how the business will be run during the earn-out period. Without them, the buyer is free to run the business for its own purposes, even where that depresses your earn-out.
Typical earn-out covenants a seller asks for
Covenant
What it protects against
Run the business in the ordinary course, consistent with past practice
Restructuring that depresses results during the period
Keep separate accounts for the business
The metric becoming impossible to measure after integration
No new group charges or cost reallocations
Overhead loaded into the business to reduce profit
Maintain agreed resources, such as the sales team and marketing budget
The business being starved of the means to hit the target
No diversion of customers, contracts or opportunities to the wider group
Revenue booked elsewhere in the group
No action whose main purpose is to reduce the earn-out
Deliberate depression of the metric
Information rights for the seller during the period
Problems discovered only when the final statement arrives
The earn-out traps
An earn-out is not inherently a bad deal. A well-structured one lets a confident seller capture upside the buyer would not pay in cash. A poorly structured one hands the buyer a legitimate route to pay you less. The difference is in the detail, and the detail is where sellers get caught.
⚠ Warning
The two traps that cost sellers the most are metric gaming and loss of control. Once you sell, the buyer decides how the business is run: which staff stay, what costs are allocated to it, whether it is integrated into a larger group. If your earn-out is measured on profit and the buyer loads it with group overhead, restructures the sales team, or diverts a key customer to another part of the business, your target moves out of reach through decisions you cannot veto. Never accept a profit-based earn-out without contractual protections over how the business is run during the earn-out period.
Three protections make an earn-out survivable: the ring-fencing covenants above; clarity on the accounting, meaning the exact definition of the metric, agreed accounting policies and a dispute mechanism; and your own role, meaning enough operational authority during the period to influence the target you are measured against. The earn-out clause is where all three are written down.
The earn-out clause: what to negotiate
The structure sets the shape of the earn-out; the earn-out clause in the sale and purchase agreement sets the detail, and the detail decides every dispute. These are the terms to work through with your corporate lawyer and accountant before you sign.
Earn-out clause checklist for sellers
Clause term
What to negotiate
Metric definition
The exact definition of revenue, gross profit or EBITDA; accounting policies consistent with the last audited accounts; a schedule of exclusions (acquisition and integration costs, group charges, one-off items)
Payment curve
Threshold, target and cap for each period; a sliding scale rather than a cliff; a catch-up if a later period overperforms
Earn-out statement
Who prepares it and by when, and your right to see the books and working papers behind it
Disputes
A short negotiation window, then expert determination by an independent accountant whose decision on the figures is final, save for manifest error
Covenants
The conduct-of-business protections above, written as obligations rather than intentions
Acceleration
The events that trigger early payment and the amount then payable
Set-off
Whether the buyer can deduct warranty claims from earn-out payments; limit it to claims agreed or finally determined
Security
How payment is secured: escrow, a parent company guarantee, or the earn-out's ranking against the buyer's lenders
Leaver terms
Whether payment depends on your continued employment, which carries a tax risk (see the UK tax section below)
★ Key Takeaway
Do not rely on anyone reading protections into an earn-out clause after the event. Everything you need, from the exclusion of group charges to the right to see the books, should be written into the clause before you sign. What is not in the clause will be argued about, at your expense, when the payment falls due.
Worked example: a sliding-scale EBITDA earn-out
Consider a seller who agrees a headline price of £10.0m: £7.0m at completion and an earn-out of up to £3.0m over two years, capped at £1.5m a year. Each year's earn-out is measured on EBITDA as the clause defines it. Nothing is paid below a £1.8m threshold, the full £1.5m is paid at or above a £2.2m target, and payment rises in a straight line in between. Because £1.5m is spread across a £0.4m band of EBITDA, every £1 of EBITDA inside the band is worth £3.75 of earn-out.
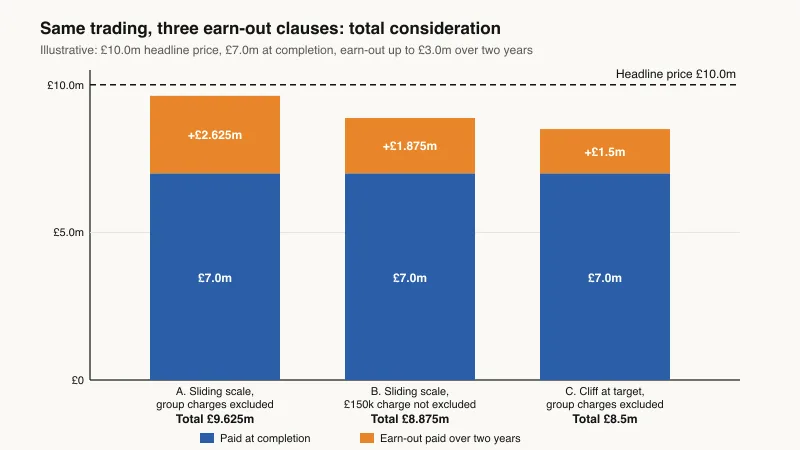
The business delivers £2.10m of earn-out EBITDA in Year 1 and £2.30m in Year 2. In Year 1 it is £0.30m into the £0.40m band, so the earn-out is 0.30 ÷ 0.40 × £1.5m = £1,125,000. Year 2 is above the target, so the cap of £1,500,000 is paid. The table compares the clause as agreed with two weaker versions of the same deal on exactly the same trading.
Worked example: three versions of the same earn-out (£)
Version of the clause
Year 1 earn-out
Year 2 earn-out
Total earn-out
Total consideration
A. Sliding scale, group charges excluded
1,125,000
1,500,000
2,625,000
9,625,000
B. Sliding scale, £150,000 a year group charge not excluded
562,500
1,312,500
1,875,000
8,875,000
C. Cliff at the £2.2m target, group charges excluded
0
1,500,000
1,500,000
8,500,000
In version B the buyer allocates a £150,000 annual management charge into the business and the clause does not exclude it. Year 1 EBITDA falls to £1.95m, which is 0.15 ÷ 0.40 of the way through the band, so £562,500 is paid. Year 2 falls to £2.15m, which is 0.35 ÷ 0.40 of the way through, so £1,312,500 is paid. One missing exclusion costs the seller £750,000. In version C the clause pays nothing below the £2.2m target, so Year 1's £2.10m earns nothing at all, and the seller receives £1,125,000 less than in version A for the same results.
Illustration: the same trading results produce total consideration of between £8.5m and £9.625m, depending only on the wording of the earn-out clause.
✔ Example
On identical performance, the gap between the best and the worst version of this clause is £1,125,000, more than 11% of the headline price. All of it depends on what the seller negotiated before signing, not on how well the business traded.
How intangible assets drive earn-out risk
Buyers use earn-outs to price the risks they cannot verify before completion, and most of those risks sit in assets that never appear on a balance sheet. The more of the value rests on relationships, people and know-how, the more of the price a buyer will want to defer, and the more likely it is that the earn-out target will be missed for reasons that have nothing to do with the market.
Customer concentration and churn
If a few customers account for a large share of revenue, a revenue or profit earn-out is effectively a bet on those customers staying through a change of ownership. Some will have change of control clauses that let them walk away; others may simply be tested by a new owner's pricing or service model. A rising churn rate during the earn-out period moves the target out of reach just as surely as a cost allocation. Our FAQ on customer concentration risk explains how buyers test for it.
Founder dependency
Where the business depends on you, the buyer faces key person risk, and an earn-out is the simplest way to keep you tied in while transferring that risk back to you. The trap is that the earn-out then measures how well you can sustain relationships after you have lost control of the business around them. Reducing that dependency before you sell, as set out in our guide to reducing founder dependency before selling, lowers the share of the price a buyer will want to defer in the first place.
Intangible risks behind an earn-out
Intangible risk
How it shows up in the earn-out
Evidence that reduces it
Customer concentration
A large part of the price deferred against revenue held by a few accounts
Contracted terms, change-of-control consents, a broadening customer base
Customer churn
A revenue or retention target missed as customers leave after completion
Retention and renewal history by cohort; documented service processes
Founder dependency
An earn-out conditional on you staying, with the tax risk that brings
A second tier of management, documented processes, relationships held by the team
Pipeline and recurring revenue
A growth target set on a pipeline the buyer cannot verify
Contracted recurring revenue, a pipeline with history and conversion rates
An earn-out only works when the thing being measured is transferable and evidenced. If the business depends on your personal relationships, an earn-out that hinges on retaining those customers is a trap you build for yourself. This is why the work of documenting your intangible assets (the customer contracts, the processes, the team that runs the business without you) is not just about defending the headline multiple. It is about being able to accept an earn-out with confidence, because the performance it measures does not walk out of the door when you step back.
Earn-outs and UK tax: a pointer, not advice
ℹ Note
This section is general information on UK tax rules, not tax advice. The treatment of an earn-out depends on the wording of the agreement and your circumstances, and the structure is far easier to get right before heads of terms than after. Take advice from a tax adviser before you agree the consideration structure.
Fixed deferred payments and the earn-out right
UK capital gains tax distinguishes deferred consideration whose amount is known or ascertainable at completion from consideration whose amount depends on events after completion. Where the deferred amount is ascertainable, even if payment is contingent, the full amount is generally brought into the gain at the date of disposal, with no discount for the wait, and the gain is adjusted later if part of it proves irrecoverable (section 48 of the Taxation of Chargeable Gains Act 1992; HMRC Capital Gains Manual CG14881 and CG14930).
A typical earn-out, whose amount depends on future profits, is unascertainable. Following Marren v Ingles and Marson v Marriage, the seller is treated as receiving two things at completion: the cash, and a right to the future payments, a chose in action. The market value of that right at completion forms part of the consideration for the shares. Each later earn-out payment is then a disposal, or part-disposal, of the right itself, with the value brought in at completion as its base cost (CG14950 and CG14970).
Two consequences are worth raising with your adviser. First, HMRC's guidance is that reliefs claimed on the original disposal, including Business Asset Disposal Relief, do not extend to later gains on the right (CG14970), and no election changes that for an earn-out paid in cash. Second, if the earn-out pays less than the value placed on the right, a loss arises; individuals may be able to elect to carry it back against gains of the tax year of the sale (sections 279A to 279D, CG15080). Where an earn-out can only be satisfied in shares or loan notes of the buyer, section 138A can treat the right as a security of the buyer, so the gain on it is deferred into the new shares or loan notes rather than charged at completion (CG58010). The seller can elect out of that treatment (section 138A(2A)), or an individual can elect under section 169Q to treat the exchange as a disposal; either brings the gain into charge at completion, where Business Asset Disposal Relief can be claimed if the conditions are met.
When an earn-out is taxed as employment income
The larger risk for an owner who stays on is that HMRC treats some or all of the earn-out as reward for employment rather than as the price of the shares. HMRC's Capital Gains Manual says deferred consideration may be assessable as employment income where the contract makes payment conditional on the seller fulfilling a contract of employment (CG14871). Employment income is usually taxed through payroll, with National Insurance contributions, rather than as a capital gain.
⚠ Warning
HMRC's Employment Related Securities Manual (ERSM110940) lists the indicators that an earn-out is sale consideration rather than remuneration: the agreement shows it is part of the price for the shares; its value reflects the value of the shares given up; it is not compensation for below-market pay; it is not conditional on future employment beyond a reasonable requirement to protect the value of the business; it carries no personal performance targets; and sellers who do not stay on receive it on the same terms. Where an earn-out is partly price and partly reward, HMRC apportions it on a just and reasonable basis. Leaver provisions that forfeit the earn-out if you resign are the clause to examine first.
Warranties and indemnities: what you are promising
Alongside the price, you will be asked to make a long list of statements about the business: that the accounts are accurate, that there is no undisclosed litigation, that the company owns the assets it claims to, that it complies with the law. These are warranties and indemnities, and they are the buyer's protection against nasty surprises after they have paid.
The distinction between the two matters. A warranty is a statement of fact; if it turns out to be untrue and the buyer suffers a loss as a result, they can claim damages, but they generally have to prove the breach caused the loss and quantify it. An indemnity is a promise to reimburse the buyer pound-for-pound for a specific, identified risk; it is a stronger, more direct remedy, and buyers push for indemnities on the risks that worry them most, such as a known tax exposure or a live dispute.
Warranty exposure is where sellers most often underestimate their liability. When you sign the sale and purchase agreement, you are personally standing behind dozens of statements about a business you may no longer own. If any of them is materially wrong, you can be pursued for it, sometimes years after completion.
Where your warranty liability is capped
The one thing you must negotiate hard on is the ceiling on your exposure. A warranty regime without proper limits is a liability with no floor.
Limit
What it caps
What a well-advised seller secures
Cap
Maximum total liability across all claims
No more than the consideration actually received, and often well below it
Time limit
How long the buyer can bring a claim
12–24 months for general warranties; longer only for tax
De minimis
Minimum size before a single claim counts
Small claims excluded so you are not nickel-and-dimed
Basket / threshold
Aggregate floor before any claim can be made
Claims only proceed once total loss passes a threshold
Without these limits, a seller can face open-ended exposure long after the money has been spent. The cap, the time limit and the thresholds are not boilerplate: they are the boundary of your risk, and they are negotiated line by line. If your earn-out is still running, check whether the buyer can set warranty claims off against it; that right can turn a disputed claim into a withheld payment.
The disclosure letter: your single most important protection
Here is the mechanism most sellers do not fully appreciate until their adviser explains it. You cannot be sued for a warranty being untrue if you told the buyer the truth before they signed. That is what the disclosure letter does: it sets out, against each warranty, the facts that qualify or contradict it. Anything fairly disclosed cannot later form the basis of a warranty claim.
ℹ Note
The disclosure letter is the seller's shield, not an administrative formality. Every known issue (the customer threatening to leave, the historic tax question, the dispute with a supplier, the software licence that is not quite watertight) should be disclosed against the relevant warranty. What you disclose, you cannot be sued for under the warranties. What you leave out, you carry. Specific indemnities are the exception: buyers usually provide that disclosure does not limit them. A thorough disclosure letter is the cheapest insurance in the whole transaction.
The discipline this demands is the same discipline that wins a good price in the first place. A seller who has already catalogued their assets, contracts and risks, and who knows exactly what the business owns, what it depends on, and where the soft spots are, can build a comprehensive disclosure letter quickly and defensibly. A seller who has not done that work is disclosing under time pressure during diligence, when omissions are most likely and most costly. The evidence you gather to defend your valuation is the same evidence that protects you under warranty.
This is where preparation before going to market pays a second dividend. The intangible assets a buyer values (the customer relationships, the owned intellectual property, the documented processes) are also the subjects of the warranties you will give. If you have identified and evidenced them in advance, you warrant them from a position of knowledge. If you have not, you are warranting statements about assets you have never properly examined.
Escrow, retention and deferred consideration
Even after the price, the warranties and the earn-out are settled, a buyer will often want to hold back cash. There are three main ways they do it, and each shifts a different risk onto the seller.
Escrow or retention
A portion of the price is held by a third party (or retained by the buyer) for a set period as security against warranty claims. If no valid claim arises, the money is released to you. If one does, the buyer draws against it first. It is your cash, held back, and worth capping tightly.
Deferred consideration
Part of the fixed price is paid in instalments after completion rather than in a single sum. Unlike an earn-out, it is not conditional on performance, but it is only as safe as the buyer's ability to pay, so the covenant strength of the buyer matters.
Earn-out consideration
The conditional portion, tied to future performance as discussed above. The riskiest of the three for a seller, because both payment and amount depend on results you may not fully control.
An escrow account protects the buyer, but you should negotiate its size and duration as hard as any other term. A retention of 10% of the price for 12 months against general warranty claims is common; a retention of 30% for three years is a different proposition entirely, and one to resist. Deferred consideration carries counterparty risk: if the buyer's business fails before the instalments are paid, you may join the queue of creditors. Understanding who is actually paying you, and whether the deferred amount is secured or guaranteed (for example through a vendor loan note with security), is essential.
There is a related mechanism worth flagging. Where a deal uses completion accounts rather than a fixed "locked box" price, the final consideration is adjusted after completion based on the actual working capital and net debt in the business on the day it changed hands. A seller who runs the working capital down before completion, or misjudges the target, can see the price adjusted downward. It is another reason the number on the heads of terms is a starting point, not a settled figure. Our comparison of locked box vs completion accounts sets out how each mechanism works, with worked examples and the working capital peg.
✔ Example
An owner sold for a headline £8m: £5.5m payable at completion, £1.5m of deferred consideration over two years, and up to £1m of earn-out on an EBITDA target. A 10% escrow (£800,000) was held back from the completion payment against warranty claims, so £4.7m reached the owner's account on completion day. The earn-out delivered £600,000, because the buyer's group overhead was allocated into the business, a risk a ring-fencing covenant would have prevented. The deferred consideration paid in full, and the escrow was released in full because the disclosure letter had been thorough and no warranty claim arose. The owner received £7.6m in total. The £400,000 difference between the headline and the outcome was structure, not price.
Staying on after the sale
Many sales require the owner to stay on, for a handover period or for the full length of an earn-out. This is not incidental to the deal; it is often central to it, because the buyer is trying to transfer the knowledge and relationships that walk out of the door when a founder leaves.
Staying on well is its own negotiation. Three things are worth settling before you sign. The first is your role and authority: are you running the business, advising it, or watching it be run by someone else while your earn-out depends on the result? The second is the terms of your service agreement: remuneration, notice, and what happens if the relationship breaks down. The third is the interaction between your employment and your earn-out: if you can be dismissed and thereby lose the influence needed to hit your target, the earn-out is worth less than it looks, and if the earn-out is forfeited when you leave, it may be taxed as employment income rather than as part of the price.
★ Key Takeaway
Keep the earn-out and the service agreement as separate as the deal allows. Pay for the work you do after completion through a market-rate salary, and pay for the shares through the consideration. Blurring the two weakens your position if the relationship breaks down, and it is the pattern HMRC looks for when deciding whether an earn-out is remuneration.
There is also a personal dimension the legal documents do not capture. You will be an employee in a business you used to own, working to someone else's plan, watching decisions made that you would have made differently. Some founders thrive on the handover; others find it corrosive. Being honest with yourself about which you are is part of deciding whether the deal structure, and the length of time it ties you in, is one you can live with.
A change of control also triggers consequences elsewhere: customer contracts with change-of-control clauses, key-person insurance, supplier agreements, and financing arrangements may all be affected the moment ownership transfers. Identifying these before completion, rather than discovering them during the buyer's diligence, is part of the same evidence discipline that protects you under warranty and defends your price.
Should you accept this earn-out?
Reduce the whole of the post-heads-of-terms deal to a single practical test and it comes down to control and evidence. Accept an earn-out when you retain enough operational authority to influence the target, when the metric is one the buyer cannot easily manipulate, when ring-fencing covenants protect the business from cost-loading, and when the performance being measured rests on transferable, documented assets rather than on your personal presence. Be wary of one when any of those conditions is missing, most of all when your consideration is tied to a profit figure the buyer controls and you do not.
The through-line from the first page to the last is preparation. The evidence that wins a strong headline price (a clear picture of what the business owns, what it depends on, and how it runs without you) is the same evidence that lets you accept an earn-out with confidence, build a disclosure letter that shields you, and negotiate warranty limits from knowledge rather than hope. The owners who get the best outcome are not the ones who negotiate hardest at completion. They are the ones who arrived at the table already knowing exactly what they were selling.
Know what you are warranting before a buyer asks
Opagio Intangibles identifies and evidences your intangible assets across Opagio 12, values them with recognised methods, and produces the Opagio Value Drivers Register and a Normalised P&L: the documents that let you disclose comprehensively, warrant from knowledge, and accept an earn-out with your eyes open. See how Opagio helps owners prepare for a sale.
Frequently Asked Questions
What is an earn-out in a business sale?
An earn-out is the part of the price that the buyer pays after completion, and only if the business meets agreed targets over a set period, usually one to three years. The seller receives a fixed sum at completion and a further, conditional sum later, measured on revenue, gross profit, EBITDA or a milestone.
How is an earn-out structured?
An earn-out structure combines a metric, a measurement period, a threshold below which nothing is paid, a payment curve up to a target, and a cap on the total. Well-drafted earn-outs add buyer covenants on how the business is run during the period, an acceleration clause for a sale or integration, and a dispute route through an independent accountant.
What should a seller negotiate in an earn-out clause?
Start with the definition of the metric and a list of costs it excludes, such as group charges and integration costs. Then negotiate a sliding scale rather than a cliff, conduct-of-business covenants, information rights, acceleration events, limits on the buyer's right to set warranty claims off against the earn-out, and security for payment.
Can a buyer avoid paying an earn-out?
A buyer can reduce an earn-out through decisions it is entitled to make as owner, such as allocating costs, restructuring teams or integrating the business, unless the clause prevents it. That is why the covenants, the exclusions from the metric and the acceleration events need to be written into the agreement rather than assumed. The buy-side view is set out in our FAQ on why acquirers use earnouts.
Is an earn-out taxed as capital or as income in the UK?
Usually as capital, but not always. An unascertainable earn-out is generally treated as a right received at completion and valued as part of the sale price, with later payments taxed as disposals of that right. If payment depends on the seller staying in employment, HMRC may treat some or all of it as employment income. This is general information, not tax advice.
Putting it together
The headline price is agreed at heads of terms. What you keep is decided afterwards: in the earn-out structure and the wording of the earn-out clause, in the warranties you give and the disclosure letter that protects you, in the escrow and deferred consideration that hold cash back, and in the terms on which you stay. Each of these shifts risk between buyer and seller, and each is negotiable. The seller who understands them keeps more of the number on the front page.
Ivan Gowan is Founder and CEO of Opagio. He spent twenty-five years in fintech, including at IG Group, before building Opagio to help owners see and evidence the intangible value in their businesses. Meet the team.
Your business is worth a multiple of its normalised earnings, and a buyer sets that multiple on assets your balance sheet never shows. Here is how the number is built, and how to move it before you sell.
Selling a business follows a defined path — preparation, teaser and IM under NDA, heads of terms, diligence, the SPA, then completion. Here is what happens at each stage, and where the price is won or lost.
A buyer prices your business through its intangible assets whether they name them or not. Here are the ones that earn a premium in a sale — and how to evidence them before diligence goes looking.
Get the latest insights on intangible asset growth and productivity delivered to your inbox.
We use essential cookies to make our website work. We'd also like to use analytics cookies to improve your experience. You can manage your preferences at any time.
Cookie Policy