How Much Can You Borrow Against a Patent? (UK)
Learn how much you can borrow against a patent in the UK: bank programmes lend up to 50%, the three lender tests, IVS valuation and a worked example.
Read more →
IP-backed lending is a business loan secured on the borrower's intellectual property, such as patents, registered trade marks, software and copyright, rather than on property or a personal guarantee. In the UK, NatWest has offered it in England and Wales since January 2024 and the Royal Bank of Scotland since June 2026, each lending up to 50% of the IP's value as assessed by an independent valuer (for the Royal Bank of Scotland, its orderly disposal value). How much you can borrow is the lower of that collateral limit and the debt your cash flow can service.
Last reviewed: October 2026. UK scope: England and Wales unless stated, with Scotland flagged where the law differs. Lender terms are taken from the lenders' own published material and change; confirm them with the lender before relying on them.
A UK bank lends against IP only when the IP is owned cleanly, can be valued on a sale basis and is registered where it can be, and when the business can service the debt from cash flow. The headline "up to 50%" applies to the lender's valuation, which for the Royal Bank of Scotland is a conservative disposal value, not to what the IP is worth to you, so the loan is usually a smaller share of your own valuation.
In IP lending, the lender takes security over specific intellectual property. If the borrower defaults, the lender can enforce that security, usually by selling or licensing the IP. Repayment is still expected to come from trading cash flow. The IP is the lender's fallback, which is why every lender tests both the asset and the business behind it.
UK banks came to this late, and for structural reasons. NatWest's own launch announcement in January 2024 described the problem plainly: high-growth businesses "generally own few tangible assets, but can be rich in IP", and struggle to use those assets as collateral. Under NatWest's approach, the bank first checks whether a borrower qualifies for standard lending on conventional security. Only if it does not will it consider using the borrower's qualifying IP as collateral.
The British Business Bank and the Intellectual Property Office (UKIPO) set out why the market had been thin in a joint 2018 report, Using Intellectual Property to Access Growth Funding. Their roundtables identified four obstacles.
| Obstacle | What it means for a borrower |
|---|---|
| Banking regulation | IP is not eligible collateral for regulatory capital, so a bank holds capital as if the loan were unsecured |
| Legal enforceability | Enforcing IP rights can be expensive and slow, and IP embedded in the business can be hard to separate and sell |
| Valuation | Valuing IP needs specialist expertise, and lenders apply a haircut for a sale on default |
| Liquidity | There is no established, liquid secondary market in which to sell IP |
The same report gave lenders a reason to look again. Matching Enterprise Finance Guarantee (EFG) loans against the UKIPO's register of rights, the British Business Bank found that companies holding patents, trade marks or registered designs defaulted less often, and cost lenders less when they did, than the EFG portfolio as a whole.
| Borrower group | Default rate | Loss rate |
|---|---|---|
| All EFG loans | 16% | 8% |
| Firms holding any registered IP right | 10% | 4% |
| Firms holding a patent | 6% | 3% |
Source: British Business Bank and UKIPO, Using Intellectual Property to Access Growth Funding (2018), figure 4.
Policy has continued in the same direction since. The UK's Modern Industrial Strategy (June 2025) committed the British Business Bank to "tackle specific barriers for IP-rich sectors, working with the Intellectual Property Office to explore how to help businesses raise debt finance secured on intangible assets". The UKIPO's Innovation and Growth Report 2025/26 records that work across government and industry. In July 2026 HM Treasury announced that the British Business Bank had allocated £500 million of the capacity in its ENABLE Guarantee programme to support lending to SMEs and scaling firms rich in IP. That support works through the lenders that use the guarantee; it is not a loan a business applies for.
The table below lists only programmes with current, public documentation from the lender itself. Where a figure appears, it is the lender's own published figure.
| Lender or body | Where | Launched | What is documented | Source |
|---|---|---|---|---|
| NatWest (High Growth IP loan) | England and Wales | 12 January 2024 | Loans from £250,000 up to 50% of the value of the firm's IP; IP valued by Inngot and revalued annually; for "high growth" businesses; over £27m lent by February 2026 | NatWest Group releases of 12 Jan 2024 and 24 Feb 2026; NatWest Sci-Net case study |
| Royal Bank of Scotland | Scotland | 3 June 2026 | Loans of £250,000 to £10m against up to 50% of the orderly disposal value found by Inngot; NatWest Group had funded £34m through the scheme | NatWest Group release of 3 Jun 2026 |
| British Business Bank | UK | Guarantees, policy and research | £500m of ENABLE Guarantee capacity allocated to lending to IP-rich SMEs and scale-ups (July 2026); joint 2018 research with the UKIPO; Industrial Strategy commitment (2025) | HM Treasury, 13 Jul 2026; BBB and UKIPO (2018); Industrial Strategy (2025) |
| Intellectual Property Office (UKIPO) | UK | Guidance | IP finance toolkit (2015) for businesses and lenders; Industrial Strategy work on lending | UKIPO toolkit (2015); Innovation and Growth Report 2025/26 |
This list is deliberately short. Specialist debt funds, venture debt providers and asset-based lenders may take security over IP as part of a wider facility, but we name a lender here only where its own current, public documentation describes an IP-backed product. A lender's absence from the table is not a statement that it does not lend against IP. For the NatWest programme in more detail, see our answer on the NatWest High Growth IP loan.
NatWest's first loan under the programme went to Sci-Net Business Solutions, an Oxfordshire software company, which borrowed £700,000 against IP that Inngot valued. In February 2026 the bank reported a £1.35m loan to Shade Station, a Manchester eyewear retailer, secured on its proprietary software and registered trade marks. The Royal Bank of Scotland's product, the first of its kind in Scotland, was made possible by the Moveable Transactions (Scotland) Act 2023, which created a registrable security over intangible property (see the security section below).
Lender terms change. Loan ranges, advance rates and eligibility tests above are as published on the dates shown. Confirm the current terms, fees and security requirements with the lender before you plan around them.
Eligibility has two halves: the IP itself, and the business that owns it. NatWest's published list of the IP its valuer may assess includes software, patents, copyrights, trade marks and registered designs. Within those classes, lenders favour rights that are identifiable, legally clean, separable from the business and capable of being sold.
| IP type | Identifiable | Transferable | Valuation evidence | Lending suitability |
|---|---|---|---|---|
| Granted patents | High (registered) | High | Income or market approach | Strong where the patent protects revenue |
| Registered trade marks | High (registered) | High | Relief from royalty | Good where the brand carries revenue |
| Proprietary software and copyright | Moderate (no UK register) | Moderate (needs code, documentation and often escrow) | Income or cost approach | Good with recurring revenue and clean title |
| Registered designs | High (registered) | High | Income approach | Product-dependent |
| Trade secrets and know-how | Low | Low (disclosure risk) | Weak | Rarely primary collateral |
| Customer relationships and data | Moderate | Low (contract and data protection limits) | Income approach | Usually within a wider facility only |
A single granted patent protecting a product that earns most of the company's revenue can be better collateral than a portfolio of defensive patents in a crowded field. Lenders value the cash flow the right protects and their ability to sell it, not the number of filings.
The business half is set by each lender. NatWest's programme is for "high growth" businesses, which it defines as showing 20% year-on-year growth in turnover over three consecutive years (minimum turnover £250,000) and/or at least £50,000 of equity or grant investment in the last two years. Lenders will also want accounts, management information and a clear use of proceeds.
To test your own position, the IP loan eligibility checklist on our lending hub is a self-assessment: three traffic-light tables covering IP registration and ownership, revenue attribution and business readiness, with a reading of what mostly green, amber or red answers mean. It does not submit an application or contact a lender.
No lender advances against IP without an independent valuation, and the premise of that valuation matters as much as the method. Three premises recur in lending.
| Premise | What it measures | How lenders use it |
|---|---|---|
| Value in use | What the IP is worth to the business that uses it, as a going concern | Usually the highest figure; the borrower's own view |
| Orderly disposal value | What the IP would fetch in a controlled sale over a reasonable period after default | The Royal Bank of Scotland (NatWest Group) lends against this figure; see orderly liquidation value, the asset-based lending term |
| Forced sale value | What a rushed sale would achieve | The floor, behind the most conservative advance rates; see forced sale value |
| Method | Best for | Approach | Limitation |
|---|---|---|---|
| Relief from royalty | Trade marks, patents, licensable software | Royalties the owner avoids by owning rather than licensing | Needs defensible comparable royalty rates |
| Multi-period excess earnings | Technology or customer assets that drive most of the earnings | Earnings left after charging for other assets used | Sensitive to forecasts and contributory charges |
| Market approach | Patents and marks with comparable sales | Prices paid for similar rights | Comparable data is thin for unique IP |
| Cost approach | Early-stage software and data | Cost to recreate the asset | Ignores the income the asset earns |
Relief from royalty is common in lending because it answers a question a lender cares about: what would a third party pay to use this IP? The multi-period excess earnings method suits portfolios where the value sits in customer-facing technology. The standards behind a lending valuation, IVS 210 and the RICS Red Book, are compared in IVS 210 vs the RICS Red Book for lending, and the method choices in IP valuation for lending.
Valuation is not a one-off. NatWest says it revalues the IP annually while the loan runs, so the value has to stay evidenced for the life of the facility.
| Check | What the lender looks for |
|---|---|
| 1. Legal title | A clean chain of title from every inventor, author and contractor to the company; registrations in force and in the company's name; no undisclosed disputes |
| 2. Encumbrances | A search of the Companies House charges register and the UKIPO registers for prior security or exclusive licences |
| 3. Revenue attribution | Evidence that the IP earns identifiable revenue, through licences, product revenue or subscriptions |
| 4. Saleability | The IP can be sold or licensed to a third party on default without destroying its value |
| 5. Durability | Remaining legal and economic life that covers the loan term, with obsolescence risk understood |
A lender sizes an IP-backed loan with two tests and offers the lower result.
Where the advance rate applies to a disposal value, a loan of "up to 50%" is usually a smaller share of what the IP is worth to you. The worked example shows by how much.
The company, the figures and the lender's terms below are illustrative assumptions, not any lender's offer. A UK software business owns its platform code and registered trade marks. An independent valuer puts their value in use at £3.0m and, on an orderly disposal premise, at £1.8m. The business generates £540,000 a year of cash available for debt service. The lender lends over five years at 10% a year, repays capital in equal instalments and requires a DSCR of at least 1.25x.
| Step | Calculation | Result |
|---|---|---|
| 1. IP value in use (valuer) | Assumption | £3,000,000 |
| 2. Orderly disposal value (valuer) | 60% of £3,000,000 (assumption) | £1,800,000 |
| 3. Collateral limit | 50% × £1,800,000 | £900,000 |
| 4. Maximum annual debt service | £540,000 ÷ 1.25 | £432,000 |
| 5. First-year debt service per £1 borrowed | 1/5 capital + 10% interest | £0.30 |
| 6. Cash-flow limit | £432,000 ÷ 0.30 | £1,440,000 |
| 7. Loan offered | Lower of £900,000 and £1,440,000 | £900,000 |
| 8. First-year debt service on £900,000 | £180,000 capital + £90,000 interest | £270,000 |
| 9. DSCR at that loan | £540,000 ÷ £270,000 | 2.00x |
The collateral test binds. The business borrows £900,000, which is 30% of the £3.0m the IP is worth in use, and comfortably clears the cash-flow test.
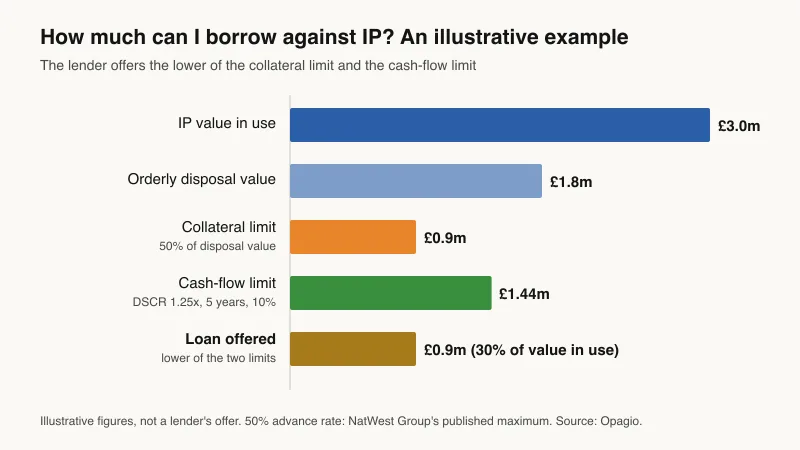
Change one input and the other test can bind. If the same business generated £300,000 of cash available for debt service, its maximum annual debt service would be £240,000 (£300,000 ÷ 1.25), and its cash-flow limit £800,000 (£240,000 ÷ 0.30). That is below the £900,000 collateral limit, so the loan would be £800,000, however valuable the IP.
To borrow more against IP, raise the lower of the two limits. Better title, registration and revenue evidence can lift the disposal value; stronger, more predictable cash flow lifts the serviceable debt. Improving the test that does not bind changes nothing.
For a first indication, the IP loan calculator on our lending hub takes your own estimates of patent, trade mark and software value and applies fixed loan-to-value assumptions to each (35% to 50% for patents, 25% to 40% for trade marks and software) to show a low and a high figure. It does not value the IP and does not test cash flow. Entered as software, the £3.0m in this example returns £750,000 to £1,200,000; a lender working from disposal value and DSCR may offer a different figure. Patent owners will find the same two tests applied to a patent in how much you can borrow against a patent, and our FAQ gives a short answer for all IP types.
A lender secures an IP-backed loan with a fixed charge or a legal mortgage (an assignment of the IP by way of security) over the named IP, often inside a debenture that also gives a floating charge over the rest of the business. Two registrations then matter in England and Wales, and a different regime applies in Scotland.
| Asset | Companies House (CA 2006 s.859A) | UKIPO record | Note |
|---|---|---|---|
| Patents and applications | Within 21 days | Yes (Patents Act 1977 s.33 priority) | Record promptly after signing |
| Registered trade marks | Within 21 days | Yes (Trade Marks Act 1994 s.25) | Unrecorded security is exposed to later acquirers |
| Copyright and software | Within 21 days | No UK register | Rely on the charge, the contract and code escrow |
| Scottish statutory pledge | Practitioners treat it as registrable within 21 days; take Scottish legal advice | UKIPO record for registered rights | The pledge is created by registration in the Register of Statutory Pledges (MT(S)A 2023 ss.42 and 48) |
Granting security does not transfer ownership: the business keeps using the IP while the loan runs. Our FAQ explains what happens to IP on default, and the security and charges reference covers ranking on insolvency.
An IP-backed facility carries the covenants of any secured term loan, plus some specific to the collateral. Expect most of the following, in a form negotiated with the lender.
| Covenant | What it requires |
|---|---|
| IP maintenance | Pay patent renewal fees, keep trade marks in use and registered, and keep software maintained and documented |
| No disposal without consent | No sale, exclusive licence or further charge over the charged IP without the lender's agreement |
| Financial covenants | A minimum DSCR or interest cover and, sometimes, a cap on debt relative to earnings, tested quarterly or annually; track your covenant headroom, not the bare minimum |
| Information | Management accounts, annual accounts and the revaluation the lender asks for |
| Notification | Prompt notice of infringement, challenges to validity, or the loss of a key customer or licensee |
Breaching an IP maintenance covenant can be a default in its own right. A lapsed patent renewal or an unused trade mark erodes the collateral and can trigger the lender's rights even when repayments are up to date.
The bank programmes above lend to the operating company against IP it owns. Larger or more complex borrowers sometimes use other structures.
An IP holdco. The IP is moved into a separate group company, which licenses it back to the operating company and charges it to the lender. Enforcement is cleaner because the lender can act against a company that holds only the IP. The cost is complexity: the licence-back must let the business keep trading if the lender enforces, and moving IP within a group has tax consequences, including transfer pricing where the companies are in different countries. Take tax and legal advice before restructuring.
Revenue-backed structures. Where IP earns contracted, recurring revenue, finance can be secured on that revenue instead of, or as well as, the IP. Our guides to revenue-based financing for intangible-heavy businesses and intangible asset securitisation cover these routes. Venture debt is a third option for equity-backed companies, underwritten mainly on the strength of the equity backing rather than the IP.
The preparation decides both the answer and the loan size. Work through these steps before you approach a lender.
Obtain written assignments from founders, employees where needed, and every contractor or agency that created code, designs or content. Put registrations in the company's name.
Search Companies House and the UKIPO registers for charges and licences you have already granted. An existing debenture may need the current lender's consent.
Show the revenue each asset supports and a forecast of cash available for debt service, so both lending tests can be run.
A lender will rely on its own valuer, but an earlier independent valuation tells you which assets carry the case and what disposal value to expect.
A lender-ready file brings these together; the IP collateral pack for lenders sets out what goes in it.
Most failed or shrunken IP-backed loans trace back to one of four avoidable mistakes.
| Pitfall | Why it costs you |
|---|---|
| Planning on value in use | The advance rate applies to the lender's valuation, often on a disposal basis, so a budget built on 50% of your own valuation overstates the loan |
| Title gaps discovered late | A missing contractor assignment or a patent filed in a founder's name can stall the loan or remove the asset from the collateral |
| Missing the 21-day window | An unregistered charge is void against a liquidator, an administrator and creditors; the lender's solicitors normally file, but the clock runs from the date the charge is created |
| Overstating the collateral | Aggressive valuations undermine the lender's confidence and the annual revaluation exposes them; conservative, well-evidenced figures travel further |
Opagio is not a lender and does not arrange or broker loans. Opagio Intangibles values each intangible asset with the Asset Valuator's recognised methods, including relief from royalty, MPEEM and with-and-without. It records the results in the Opagio Value Drivers Register, the evidence base a lender's valuer and credit team can test. For lender guides, the eligibility checklist and the calculator in one place, start at the Opagio lending hub.
Run the eligibility checklist, size a first range with the IP loan calculator, and see how Opagio Intangibles builds the valuation evidence a lender will test.
IP-backed lending is a loan secured on a company's intellectual property, such as patents, registered trade marks, software and copyright. The lender takes a charge over the IP and can enforce it on default, but expects repayment from trading cash flow. In the UK, NatWest and the Royal Bank of Scotland run published programmes.
NatWest has offered its High Growth IP loan in England and Wales since January 2024, and the Royal Bank of Scotland launched an IP lending product in Scotland on 3 June 2026. Both use Inngot as the independent IP valuer. Other lenders may take IP security within wider facilities; check with each lender directly.
A lender offers the lower of two limits: its advance rate applied to its valuation of the IP, and the debt your cash flow can service at its required DSCR. NatWest and the Royal Bank of Scotland lend up to 50% of the independently assessed IP value (orderly disposal value at the Royal Bank of Scotland), so the loan is usually a smaller share of the IP's value in use. In our illustrative example it is 30%.
Granted patents, registered trade marks, registered designs, copyright and proprietary software can all qualify, and NatWest names each of them. The IP must be owned cleanly by the borrowing company, capable of being valued and sold, and linked to revenue. Trade secrets are rarely accepted as primary collateral.
The company, or anyone interested in the charge, delivers a statement of particulars to Companies House within 21 days, beginning with the day after the charge is created (Companies Act 2006 s.859A). The lender should also record its security at the UKIPO for patents and trade marks, to protect its priority against later transactions. Scotland adds the statutory pledge. See our Section 859A explainer.
NatWest Group press releases of 12 January 2024, 24 February 2026 and 3 June 2026; NatWest, "Sci-Net secures market-first IP-backed loan" (2024); HM Government, The UK's Modern Industrial Strategy (June 2025), pp. 49–50; HM Treasury press release on the Growth Guarantee Scheme and ENABLE Guarantees (13 July 2026); The Patent Office Innovation and Growth Report 2025/26 (July 2026); British Business Bank and Intellectual Property Office, Using Intellectual Property to Access Growth Funding (2018); Intellectual Property Office, Banking on IP: IP finance toolkit (March 2015); Companies Act 2006 ss.859A and 859H; Patents Act 1977 s.33; Trade Marks Act 1994 s.25; Moveable Transactions (Scotland) Act 2023 ss.42, 47 and 48.
Tony Hillier is Chairman of Opagio. He holds an MA from Balliol College, Oxford and an MBA with distinction. Tony held executive board positions at NM Rothschild & Sons and GEC Finance, and a non-executive directorship at Financial Security Assurance in New York, where he specialised in structured finance, asset-backed securities and cross-border leasing. Meet the team.
Evidence the intangible assets a UK lender can assess as collateral.
A 20-second check — do any of these apply to your business?
Learn how much you can borrow against a patent in the UK: bank programmes lend up to 50%, the three lender tests, IVS valuation and a worked example.
Read more →
Bank of England data shows UK SMEs in high-growth sectors borrow over about 70 months, against 108 elsewhere. What the loan maturity gap costs intangible-rich SMEs, and what evidence can change.
Read more →
How companies can use proprietary data assets as collateral for financing. Covers data valuation methods, governance requirements, emerging lending structures, and the regulatory landscape shaping data-backed finance. Abstract visualization of data streams flowing into financial structures with network nodes and warm accent colours
Read more →Get the latest insights on intangible asset growth and productivity delivered to your inbox.